
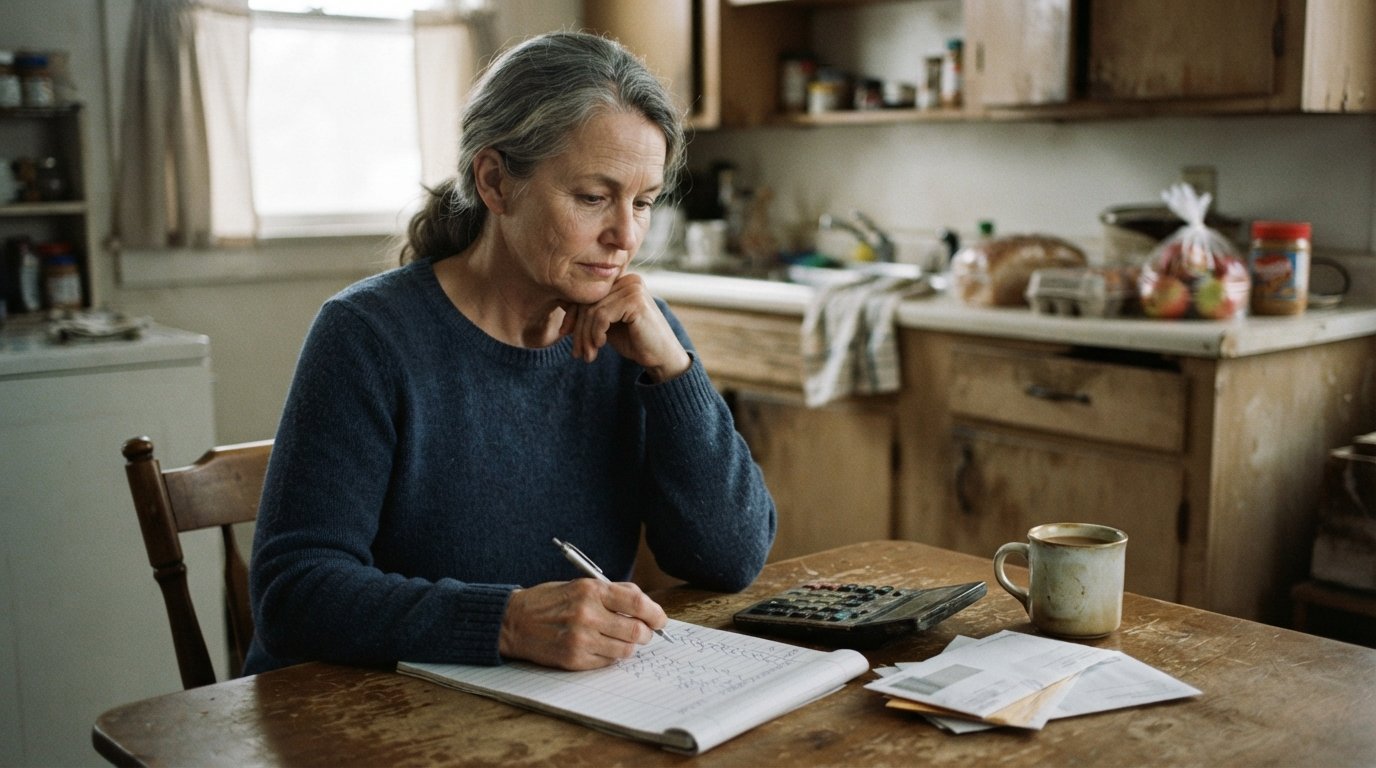
Bare Bones Budget for Extreme Financial Hardship
A bare bones budget for extreme financial hardship covers only survival essentials, freeing up money to negotiate debt relief and avoid new borrowing.
By Aria Caldwell
When a job loss, a medical emergency, or a sudden drop in income hits, the numbers on your normal budget stop making sense. Rent is due, groceries are nonnegotiable, and every other line item suddenly looks like a luxury. This is where a bare bones budget for extreme financial hardship becomes not just useful but essential. It is the stripped down, survival focused version of your household spending plan, designed to keep a roof over your head and food on the table while you stabilize. If you are facing overwhelming unsecured debt such as credit cards, personal loans, or medical bills, a bare bones budget can also buy you the breathing room you need to explore structured relief options. In our guide on 2026 federal hardship debt programs, we explain how recent changes may affect your eligibility for certain protections and relief.
What Is a Bare Bones Budget and Why It Matters in a Crisis
A bare bones budget is a spending plan that covers only the absolute necessities for survival and basic functioning. It is not about cutting back on dining out or subscription services, although those cuts happen too. It is about asking one question for every dollar: if I do not spend this, will my family be unsafe, hungry, or without shelter? If the answer is no, the expense goes, at least for now.
In extreme financial hardship, your income may have dropped suddenly or disappeared entirely. A traditional budget that assumes a steady paycheck will fail immediately. A bare bones budget, by contrast, is built for volatility. It prioritizes four walls: housing, utilities, food, and transportation to work or medical care. Everything else is secondary. This hierarchy is not arbitrary. Without shelter or basic utilities, it becomes nearly impossible to recover. Without food, your health deteriorates. Without transportation, you cannot earn or attend medical appointments.
The psychological benefit is just as important. When you are drowning in debt and facing collection calls, a bare bones budget gives you a sense of control. You are no longer reacting to every bill that arrives. You are making deliberate choices about which obligations to meet and which to pause. That clarity can reduce the paralyzing stress that often accompanies financial hardship.
How to Build Your Bare Bones Budget Step by Step
Building a bare bones budget does not require fancy software or a finance degree. It requires honesty, a list of your essential expenses, and a willingness to make temporary sacrifices. Start by calculating your total monthly income from all sources: wages, unemployment benefits, side gigs, child support, or any other regular deposits. If your income fluctuates, use the lowest month from the past three months as your baseline. This conservative approach prevents you from overspending in a good month and falling short in a bad one.
Next, list your essential expenses in order of priority. Housing comes first. That means rent or mortgage, property taxes if applicable, and required insurance. Utilities come second: electricity, water, heat, and basic internet if it is required for work or job searches. Food comes third, but only staples and basic nutrition, not restaurant meals or specialty items. Transportation comes fourth, including gas, public transit passes, and essential car maintenance. Medical care and prescriptions come fifth. Minimum debt payments come last, and only if there is money left after the first five categories.
Here is a simple framework for categorizing your expenses:
- Tier 1 (Survival): Housing, utilities, food, transportation, medical care.
- Tier 2 (Obligations): Minimum debt payments, child support, court ordered payments.
- Tier 3 (Temporary cuts): Subscriptions, dining out, entertainment, new clothing, gym memberships.
- Tier 4 (Eliminate): Luxury items, nonessential travel, high interest loans that can be paused or renegotiated.
Once you have your tiers, allocate every dollar of income to Tier 1 first. If money remains, move to Tier 2. Tier 3 and Tier 4 expenses are paused until your financial situation improves. This does not mean you will never enjoy a meal out again. It means that for now, survival takes precedence.
What to Include and What to Cut
The line between essential and nonessential can feel blurry when you are under stress. A few guiding principles can help. Include anything that prevents immediate harm to your health, safety, or ability to earn income. That includes rent, mortgage, utilities, basic groceries, necessary medications, and transportation to work. If you have children, include childcare that is required for you to work, and basic school supplies.
Cut anything that is optional or deferrable. This includes streaming services, gym memberships, magazine subscriptions, and regular dining out. It also includes nonessential clothing, electronics, and home decor. If you have multiple debt payments, consider whether some can be paused through hardship programs or negotiated down. For example, many credit card issuers offer temporary hardship plans that reduce or suspend payments for a few months. Medical bills can often be negotiated or placed on interest free payment plans.
One area where people often overspend during a crisis is convenience. Takeout food, rideshare services, and last minute purchases can drain a bare bones budget quickly. Plan ahead: cook at home, use public transit or carpool, and make a list before you shop. These small changes add up.
If you are considering a loan to cover gaps, be cautious. High interest payday loans and title loans can deepen your hardship. If you must borrow, explore all options first. You can compare loan offers from multiple lenders to see if a lower interest personal loan or installment loan might be less harmful than a payday loan. However, keep in mind that borrowing should be a last resort, not a first step.
Tracking and Adjusting Your Bare Bones Budget
A budget is only useful if you track it. During extreme hardship, you should review your budget weekly, not monthly. Income and expenses can change quickly. Use a simple spreadsheet, a notebook, or a free budgeting app. Record every dollar that comes in and every dollar that goes out. At the end of each week, compare your actual spending to your plan. If you overspent in one category, adjust the next week.
Be prepared to make hard choices. If your income drops further, you may need to move to an even more austere version of your bare bones budget. That could mean cutting internet at home and using library Wi-Fi, reducing your food budget to rice and beans, or selling a car and using public transit. These choices are painful, but they are temporary. The goal is to survive the crisis without accumulating new debt or losing your home.
As your situation stabilizes, you can gradually add back Tier 3 expenses. But do not rush. Keep your bare bones budget in place until you have a steady income and a small emergency fund. Even after you recover, the habits you build during this time, such as meal planning, tracking expenses, and prioritizing needs over wants, will serve you well.
How a Bare Bones Budget Fits with Debt Relief
If you are dealing with overwhelming unsecured debt, a bare bones budget alone will not solve the problem. It can keep you afloat, but it will not reduce what you owe. That is where structured debt relief comes in. Debt settlement, for example, involves negotiating with creditors to accept less than the full balance. It is designed for people facing genuine hardship who have already explored other options like debt management plans or credit counseling.
A bare bones budget can actually make debt settlement more effective. When you have a clear picture of your essential expenses, you know exactly how much you can afford to put toward a settlement program each month. You also demonstrate to creditors that you are in hardship and cannot pay more. Many settlement companies require a hardship letter and a budget worksheet, and a bare bones budget provides both.
It is important to understand the trade offs. Debt settlement can negatively impact your credit score, and forgiven debt may be taxable. You should consult a qualified financial advisor or tax professional before enrolling. Also, compare multiple options. Debtsend is a free matching service that connects you with third party partners who offer debt settlement, consolidation style plans, and other relief options. You can start with a no obligation debt assessment to see what you might qualify for.
Remember that you are not alone. Millions of Americans face financial hardship every year, and there are legitimate programs designed to help. A bare bones budget is your first line of defense. It buys you time and clarity. From there, you can explore relief options and build a path toward financial recovery.
Extreme financial hardship is frightening, but it is not permanent. By creating a bare bones budget, you take control of what you can control: your spending. You protect your family's basic needs and reduce the chaos that comes with overwhelming debt. As you stabilize, reach out for help. Whether through a debt relief program, a credit counselor, or a supportive community, you do not have to navigate this alone. Small, consistent steps can lead you back to solid ground.