Credit Card Debt Solutions for a Fixed Income
Credit card debt solutions for people living on a fixed income can reduce balances and fit a small monthly budget. See which programs protect your benefits.
By Matteo Alvarez
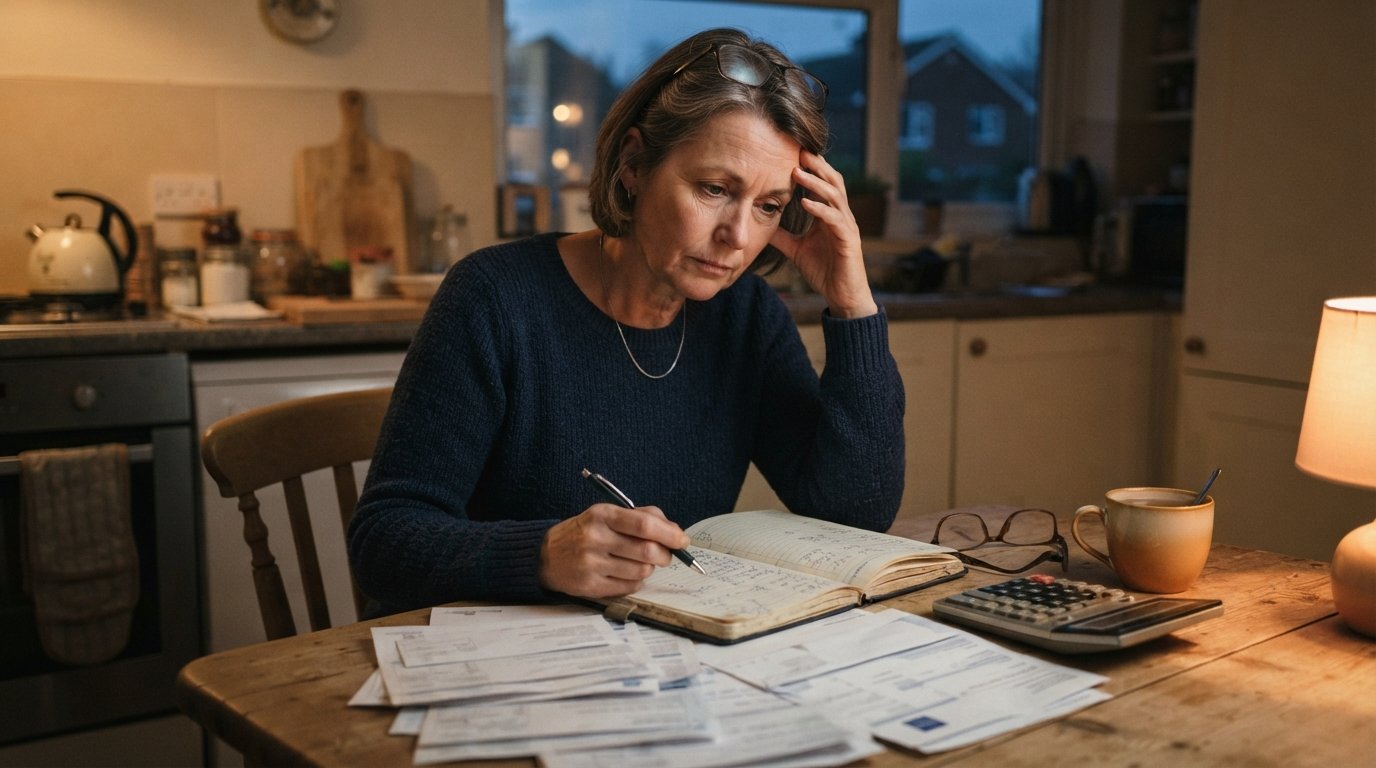
Living on a fixed income means every dollar is already spoken for before it arrives. When credit card bills pile up and minimum payments start competing with rent, groceries, and medication, the stress can feel impossible to escape. The good news is that there are real, workable credit card debt solutions for people living on a fixed income, and they do not require a sudden windfall or a second job. They require understanding your protections, choosing the right program, and building a budget that leaves room to resolve the debt without sacrificing basic needs.
Why Standard Minimum Payments Fail Fixed-Income Households
Credit card minimum payments are calculated as a small percentage of the balance, often between 1 and 3 percent, plus interest and fees. For someone earning a steady salary that grows over time, this structure can work. For someone on Social Security, a pension, or disability payments, it often does not. A single emergency, such as a car repair or a medical copay, can push the account over the limit and trigger penalty rates that exceed 29 percent annually. Once that happens, the minimum payment climbs even as the balance barely moves.
The deeper problem is that fixed incomes are fixed. There is no bonus, no overtime, and no raise to absorb a higher payment. When a creditor raises the minimum due or a variable interest rate jumps, the household has nowhere to pull the difference from except other essentials. Many people begin paying credit cards with money budgeted for food or utilities, which creates a second layer of debt and risk. This is why traditional minimum-payment plans so often collapse for seniors and disabled individuals, and why more structured credit card debt solutions for people living on a fixed income are necessary.
There is also a psychological trap. Creditors and collectors often imply that missing a payment is a moral failure. In reality, it is a math problem. Once you accept that the payment schedule no longer fits your income, you can stop juggling and start looking at options that actually match your cash flow.
Protections for Social Security and Fixed-Income Sources
One of the most important facts for anyone on a fixed income is that Social Security benefits are generally protected from most creditors. Under federal law, Social Security income cannot be garnished by credit card companies, medical providers, or other unsecured creditors. Only a few exceptions exist, such as federal student loans, taxes, and child support. This protection applies even if a creditor sues and obtains a judgment, though the rules for bank accounts can vary by state and require action to claim the exemption.
This protection matters because it changes the negotiation dynamic. A creditor cannot simply take your benefits. They can call, send letters, and sue, but they cannot reach the money that keeps you housed and fed. Understanding this reduces fear and gives you room to negotiate from a position of stability rather than panic. If you receive Social Security, Supplemental Security Income, or certain disability benefits, you should keep them in a separate account and be prepared to show documentation if a bank levy is attempted.
Other fixed-income sources, such as pensions and Veterans Affairs benefits, have different rules. Some pensions can be garnished under certain circumstances, and VA benefits have their own protections. It is worth confirming exactly which income streams are protected in your state before you engage with collectors, so you know what you are working with.
Programs and Negotiations That Work With Low Monthly Payments
When your budget is tight, the goal is to find a solution that reduces the total amount you owe and accepts a payment you can actually sustain. Several paths exist, and the right one depends on your balance, your creditors, and how far behind you are. Here are the main options to evaluate:
- Debt settlement: A negotiated agreement to pay less than the full balance, often in a lump sum or a short series of payments. This can work well for people with limited income because it focuses on what you can realistically pay, and programs can be structured around monthly amounts you can afford.
- Debt management plans: Nonprofit credit counseling agencies can negotiate lower interest rates and combine payments into one monthly amount. These plans work best when you can still afford a modest payment and want to avoid the credit impact of settlement.
- Hardship programs: Many major issuers have internal programs that temporarily reduce interest or payments for customers facing financial hardship. You must call and ask, and the terms vary widely.
- Credit card debt forgiveness negotiations: Some creditors will accept a reduced payoff if you can demonstrate hardship and make a lump-sum offer. This is essentially a do-it-yourself settlement and requires careful documentation.
For many fixed-income households, debt settlement is the most realistic path because it is designed around a reduced total balance rather than a restructured payment schedule. A reputable matching service can connect you with partners who negotiate on your behalf, and the initial evaluation is typically free. If you are in California, our guide on 5 ways to get credit card debt help in Los Angeles explains how local options compare. The key is to avoid any program that demands a large upfront fee or promises results before a negotiation has happened.
When negotiating directly, always get the agreement in writing before making a payment. Confirm that the letter states the account will be considered settled and that the remaining balance will not be sold to another collector. Keep records of every call, including dates, names, and what was promised.
Building a Bare-Bones Budget That Leaves Room for a Settlement Payment
You cannot negotiate your way out of debt if your budget has no room for a payment. A bare-bones budget starts with the non-negotiables: housing, utilities, food, transportation, insurance, and medical costs. Add the minimum payments on any secured debts, such as a car loan, because losing a vehicle can cost you a job or access to medical care. What remains is the amount available for unsecured credit card debt.
For many people on a fixed income, that number is small, sometimes under $100 per month. That is acceptable. Settlement programs can be built around small monthly deposits into a dedicated account, which accumulate until there is enough to make an offer. The discipline of saving a fixed amount each month is often more important than the size of the amount. If you can set aside $50 or $75 monthly, you are building the leverage you need.
It also helps to separate needs from wants with a simple rule: if losing it would threaten your housing, health, or ability to earn, it is a need. Everything else can be paused while you resolve the debt. This is not forever. It is a temporary structure that protects you while you work through a program.
How to Choose the Right Solution for Your Situation
No single solution fits every fixed-income household. The right choice depends on how much you owe, how many creditors you have, whether you are already behind, and how much you can set aside each month. A practical way to decide is to compare options on four factors: total cost, monthly payment, credit impact, and timeline. Debt settlement typically reduces the total balance but has a negative credit impact and takes two to four years. Debt management preserves credit better but requires a payment that covers the full balance plus reduced interest. Hardship programs are temporary and vary by issuer.
It is also wise to compare multiple offers before committing. A free debt relief matching service can present options from several partners, which helps you see the range of what is available without committing to the first company that calls. Be cautious of any organization that charges fees before settling a debt, guarantees a specific outcome, or asks you to stop communicating with creditors entirely without a clear plan.
If your situation includes an immediate cash shortfall, such as a necessary car repair or a medical bill that cannot wait, a short-term loan may be part of the picture. Services like AdvanceCash connect consumers with third-party lenders for short-term and installment loan options, which can help bridge a gap while you work on a longer-term debt solution. Use any short-term borrowing carefully and only after confirming the repayment terms fit your fixed budget.
Steps to Take This Month
You do not need to solve everything at once. A clear sequence of steps can turn a overwhelming situation into a manageable project. Start by listing every credit card balance, interest rate, and minimum payment. Then list your income and essential expenses. The gap between them tells you what you can realistically commit to a debt solution.
- Gather your statements and confirm which income sources are protected from garnishment.
- Calculate a bare-bones budget and identify the monthly amount you can set aside for debt.
- Contact a nonprofit credit counselor or a reputable debt relief matching service for a free evaluation.
- Compare at least two options and ask about total cost, timeline, and credit impact.
- Get any settlement agreement in writing before making a payment.
After you choose a path, review your progress every three months. Fixed incomes can change when benefits adjust, and a program that was unaffordable in January may become workable in July. Staying in contact with your program and updating your budget keeps the plan realistic.
Avoiding Scams and Predatory Offers
Financial hardship attracts predators. Common warning signs include upfront fees before any debt is settled, promises that a specific balance will be eliminated, pressure to sign immediately, and requests to stop paying creditors without a written plan. Legitimate debt relief providers explain the risks, including credit score impact and potential tax consequences of forgiven debt, and they do not guarantee outcomes.
Verify any company against state licensing records and consumer protection agencies. Read reviews beyond the company website, and ask for the written agreement before sharing bank account details. If a caller claims to be from the IRS or a government program and demands immediate payment, hang up and verify independently. These steps protect both your money and your peace of mind.
Credit card debt on a fixed income is difficult, but it is not hopeless. By understanding your protections, choosing a program built around a realistic monthly amount, and guarding against scams, you can move from crisis to a structured plan. Start with one call, one budget, and one honest look at the numbers. The path forward is smaller than it appears, and it begins with a single step.