
Debt Settlement Agreement Defaulted: What Happens Now in 2026
Defaulted on a debt settlement agreement? Find out what happens now and how to protect yourself. Call 8336708023 for expert guidance.
By Iris Calderwyn
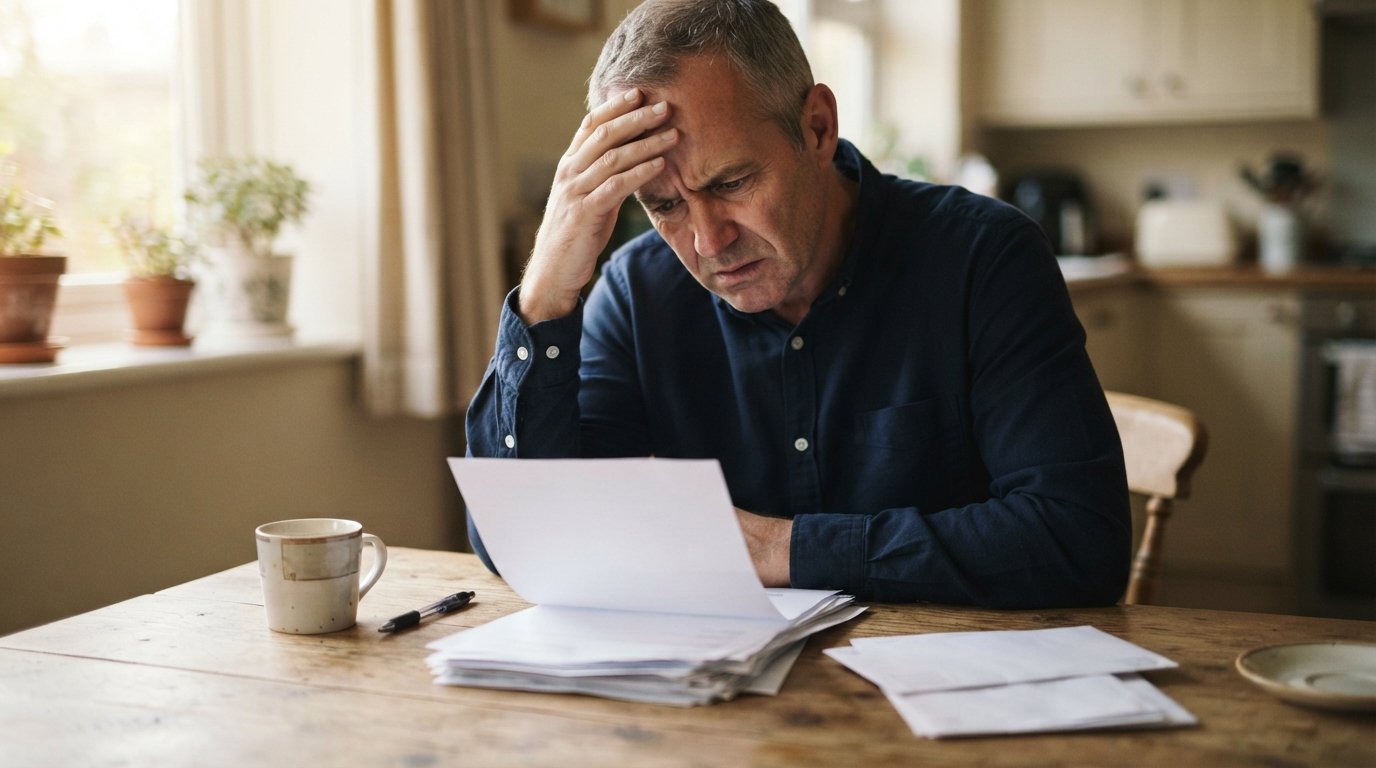
Missing a payment on a debt settlement agreement can feel like watching a carefully built bridge collapse in real time. You entered the program hoping to resolve overwhelming unsecured debt, and now a default notice sits on your kitchen table. The good news is that a default is not the end of your financial story. It is a pivot point, and understanding exactly what happens next gives you the power to choose your response instead of reacting in panic.
This guide walks through the real-world consequences of defaulting on a debt settlement agreement, the timeline creditors and collection agencies typically follow, and the concrete steps you can take to protect yourself. Whether you missed one payment or several, you will learn how to assess your situation, communicate with the right parties, and explore alternatives that may still reduce your total debt burden.
What Defaulting on a Debt Settlement Agreement Actually Means
A debt settlement agreement is a contract. You promise to pay a specific amount, often in a lump sum or a series of monthly installments, and in exchange the creditor agrees to accept less than the full balance owed and release you from the remaining debt. When you miss a payment or fail to fund the agreed-upon savings account, you breach that contract. The creditor is no longer legally obligated to honor the reduced payoff amount.
Most settlement agreements include a default clause that spells out exactly what happens if you stop paying. Common provisions include reinstatement of the original balance, acceleration of the remaining payments, and the creditor's right to resume collection activity. Some agreements also state that any payments already made will be applied to the original debt rather than the settled amount, which means you could lose the benefit of everything you have paid so far.
The specific consequences depend on several factors: whether the settlement was negotiated directly with the original creditor or through a third-party debt settlement company, whether the agreement was documented in writing, and whether the creditor had already charged off the account or sold it to a collection agency. In nearly every scenario, however, default triggers a chain of events that you need to understand quickly.
Immediate Consequences: What Happens in the First 30 to 60 Days
The first few weeks after a default are critical. Creditors and collection agencies typically follow a predictable playbook, and knowing what to expect helps you avoid costly mistakes.
Within the first week or two, you will likely receive a written notice of default. This letter usually states the amount you failed to pay, the deadline to cure the default (bring the account current), and the consequences if you do not. Read this letter carefully. Some agreements allow a grace period of 10 to 30 days during which you can make the missed payment plus any late fees and keep the settlement intact.
If you do not cure the default within the specified window, the creditor may take the following actions:
- Reinstate the full original balance, minus any payments you have already made
- Resume collection calls and letters, sometimes with increased urgency
- Report the default to credit bureaus, which can damage your credit score further
- Refer the account to a collection agency or an attorney for legal action
- File a lawsuit to obtain a judgment against you
The last two items on that list are the most serious. A lawsuit can lead to wage garnishment, bank account levies, or property liens, depending on your state's laws. That said, not every creditor sues immediately. Many will try to negotiate a new settlement or payment plan first, especially if they believe you still have the ability to pay something.
It is also worth noting that if you were working with a debt settlement company, they may contact you to discuss options. Some companies will negotiate a new agreement on your behalf, while others may terminate their services. Review your contract with the settlement company to understand your rights and obligations.
Credit Score and Tax Implications of a Default
Defaulting on a settlement agreement affects more than your immediate cash flow. It can also impact your credit score and create unexpected tax liabilities.
From a credit reporting perspective, a default may be reported as a missed payment or a collection account. If the original creditor had already charged off the debt, the charge-off remains on your report for seven years from the date of first delinquency. A new default does not reset that clock, but it can add a fresh negative mark that lowers your score. The exact impact depends on your overall credit profile, but a drop of 50 to 100 points is not uncommon.
On the tax side, forgiven debt is generally considered taxable income by the IRS. If a creditor agrees to accept less than you owe and you default on that agreement, the forgiven amount may no longer apply. However, if you later negotiate a new settlement, the forgiven portion could still trigger a tax bill. You may qualify for the insolvency exclusion if your total debts exceed your total assets, but you will need to file the appropriate IRS form. Consulting a tax professional is always wise before assuming you owe nothing.
For a deeper look at the ripple effects of breaking a settlement agreement, including legal and financial consequences, see this guide on breaking a debt settlement agreement. It outlines seven specific outcomes that can help you anticipate what is coming next.
Legal Action: When Creditors Sue After a Default
One of the most feared outcomes of defaulting on a settlement agreement is a lawsuit. While not every creditor sues, those that do are often motivated by the belief that you have assets or income they can reach through a judgment.
If you receive a summons and complaint, do not ignore it. Failing to respond can result in a default judgment against you, which gives the creditor the right to pursue garnishment or levies without further court involvement. If you respond, you have the opportunity to present a defense, negotiate a new settlement, or request a payment plan.
Common defenses to debt collection lawsuits include:
- The statute of limitations has expired on the debt
- The creditor cannot prove they own the debt (especially common with debt buyers)
- The amount claimed is incorrect or includes unauthorized fees
- You were a victim of identity theft
- The debt was discharged in bankruptcy
Even if you do not have a strong legal defense, showing up and negotiating can lead to a better outcome than simply ignoring the lawsuit. Many creditors are willing to settle for a lump sum or a structured payment plan to avoid the time and expense of a trial.
If you are facing a lawsuit and feel overwhelmed, consider consulting a consumer protection attorney. Many offer free initial consultations and can help you understand your rights under the Fair Debt Collection Practices Act (FDCPA) and your state's consumer protection laws.
How to Respond: Steps to Take Immediately After a Default
When you realize you have defaulted on your debt settlement agreement, the worst thing you can do is nothing. Taking action, even imperfect action, puts you back in control. Here is a step-by-step framework to guide your response.
- Review your agreement. Locate the original settlement contract and read the default clause carefully. Note any cure periods, reinstatement terms, and communication requirements.
- Contact the creditor or settlement company. Call or write to explain your situation. Be honest about why you missed the payment and ask what options are available. Some creditors will reinstate the agreement if you make the missed payment promptly.
- Document everything. Keep a log of all phone calls, emails, and letters. Note the date, time, representative's name, and what was discussed. This record can be invaluable if a dispute arises later.
- Explore your alternatives. If the settlement cannot be salvaged, consider other options such as negotiating a new settlement, enrolling in a debt management plan, or consulting a bankruptcy attorney to understand your rights.
- Protect your income and assets. If a lawsuit seems likely, learn about your state's garnishment and exemption laws. In some states, certain income (such as Social Security) is protected from collection.
Timing matters. The sooner you reach out, the more options you typically have. Creditors are often more flexible early in the process than after they have incurred legal fees.
If you need short-term funds to cover essential expenses while you sort out your debt situation, you might explore options through services like ExpressCash, which connects consumers with third-party lenders for payday loans, installment loans, and lines of credit. These are not debt settlement solutions, but they can provide a bridge when you are facing an unexpected bill and need to avoid re-defaulting on a settlement arrangement.
Can You Restart or Renegotiate a Defaulted Settlement?
Yes, in many cases you can restart or renegotiate a settlement after a default. Creditors are businesses, and they generally prefer to recover something rather than nothing. If you can demonstrate a genuine hardship and a willingness to pay, they may agree to a new arrangement.
The key is to approach the conversation strategically. Before you call, gather documentation of your income, expenses, and any changes in your financial situation (such as a job loss or medical emergency). Be prepared to make a specific offer, whether that is a lump sum, a short payment plan, or a reduced monthly amount.
If you were working with a debt settlement company, ask whether they can renegotiate on your behalf. Some companies include this as part of their service, while others charge an additional fee. If you are negotiating on your own, consider sending a written proposal via certified mail so you have proof of delivery.
Keep in mind that a new settlement may come with less favorable terms than the original. The creditor may demand a larger down payment or a shorter repayment window. That is okay. The goal is to resolve the debt in a way that is sustainable for you.
Alternatives to Consider If the Settlement Is Beyond Repair
If renegotiating the settlement is not possible, you still have options. The right choice depends on your income, assets, and the types of debt you owe.
- Debt management plan (DMP): A nonprofit credit counseling agency negotiates lower interest rates and one monthly payment. This can be a good fit if you have steady income and want to avoid bankruptcy.
- Chapter 7 bankruptcy: Liquidates non-exempt assets to pay creditors, with most unsecured debt discharged. It can provide a fresh start but has long-lasting credit implications.
- Chapter 13 bankruptcy: Reorganizes debt into a 3- to 5-year repayment plan. It can stop foreclosure and allow you to catch up on secured debts.
- Debt consolidation loan: Combines multiple debts into one loan with a fixed interest rate. This works best if you have good credit and can qualify for a lower rate.
- Self-negotiated settlement: You contact creditors directly and negotiate a lump-sum payoff. This requires time and persistence but can save money.
Each option has trade-offs. Bankruptcy, for example, can stay on your credit report for 7 to 10 years, but it may be the only way to eliminate overwhelming debt. A DMP can help you repay in full but may take several years. Weigh the pros and cons carefully, and consider speaking with a financial advisor or bankruptcy attorney before making a decision.
At Debtsend, we help individuals in the United States overcome unsecured debt through structured settlement programs. If you are exploring alternatives to bankruptcy or debt management plans, our free matching service can connect you with partners who may offer personalized solutions. There is no obligation, and the initial consultation is free. You can estimate your savings in minutes and see whether a debt settlement program is right for you.
Protecting Yourself from Future Defaults
Once you have resolved the immediate crisis, it is important to take steps to prevent another default. The most common reasons people default on settlement agreements are unexpected expenses, loss of income, or a mismatch between the payment schedule and their actual cash flow.
To avoid a repeat situation, consider building a small emergency fund before committing to a settlement payment plan. Even $500 to $1,000 can cover minor emergencies and keep you on track. Also, make sure the payment amount is realistic. If the monthly payment leaves you with nothing left for basic needs, the plan is too aggressive. It is better to negotiate a longer term with smaller payments than to agree to something you cannot sustain.
Finally, stay in communication with your creditor or settlement company. If you see trouble coming, call them before you miss a payment. Many are willing to work with you if you are proactive. It is when you go silent that they assume the worst and escalate.
Your Next Steps After a Defaulted Debt Settlement Agreement
Defaulting on a debt settlement agreement is stressful, but it is not the end of the road. The key is to act quickly, communicate openly, and explore every option available to you. Whether you renegotiate the settlement, enroll in a debt management plan, or decide that bankruptcy is the right path, you have the power to make a choice that moves you toward financial recovery.
Start by reviewing your agreement and contacting the creditor. Document everything, and do not be afraid to ask for help. If you are unsure where to turn, consider reaching out to a nonprofit credit counselor or a consumer protection attorney. And if you want to explore debt settlement as a solution for unsecured debt, Debtsend can connect you with partners who may be able to help. Call us at 8336708023 or visit our website to learn more. Your financial freedom is worth fighting for.