
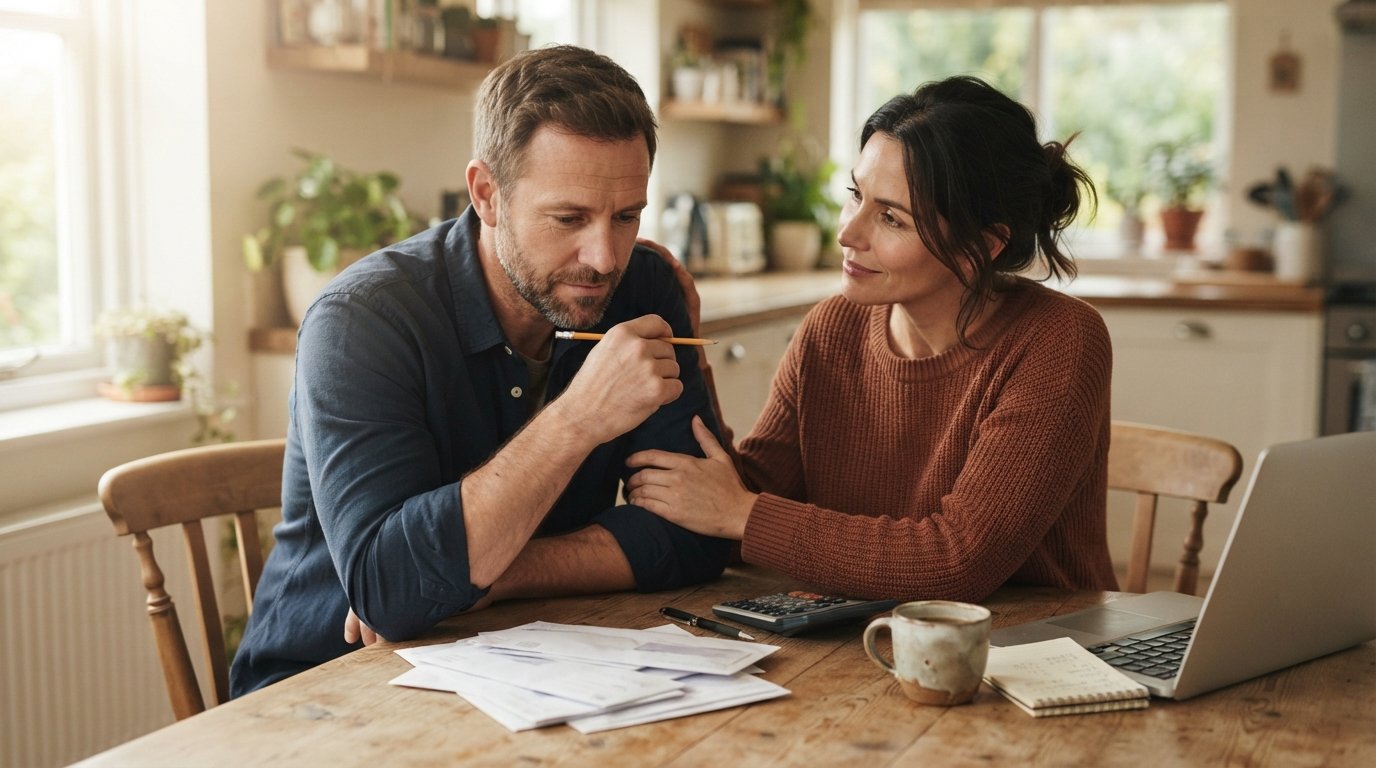
Emotional Impact of Debt on Marriage and How Couples Cope
Debt strains trust and intimacy, but couples can cope. Call 8336708023 to explore structured relief options and start healing together.
By Corey Phillips
Money arguments happen in nearly every marriage, but when the conflict centers on mounting debt, the stakes feel higher and the wounds cut deeper. The emotional impact of debt on marriage and how couples cope has become a defining issue for millions of households across the United States. Credit card balances, personal loans, medical bills, and collection accounts do more than strain a bank account. They strain trust, intimacy, and the sense of shared purpose that holds a partnership together. Understanding why debt triggers such powerful emotions is the first step toward protecting both your relationship and your financial future.
Why Debt Hits the Marriage So Hard
Debt is rarely just a numbers problem. It carries shame, fear, and the quiet belief that you should have known better. When one or both spouses carry that weight, everyday conversations can turn into accusations, silence, or avoidance. Research and clinical experience consistently show that financial stress is among the top predictors of marital conflict and, in some studies, divorce. The reason is simple: money touches nearly every decision a couple makes, from where they live to whether they have children to how they retire.
The emotional impact of debt on marriage also depends on how the debt originated. A spouse who accumulated balances through a medical emergency may feel victimized by circumstance, while a spouse who overspent may feel defensive and judged. These differing narratives create a gap in perception. One partner sees bad luck, the other sees irresponsibility. Without honest communication, that gap widens into resentment.
Debt can also flip the power dynamic in a relationship. The partner who earns more may feel entitled to make financial decisions, while the partner who earns less may feel powerless or resentful. When debt is involved, this imbalance intensifies. Couples who once made decisions as equals may find themselves negotiating from positions of guilt, blame, or fear.
The Common Emotional Responses Debt Triggers
Before couples can cope effectively, they need to recognize the emotions in play. Debt does not simply create worry. It produces a predictable set of emotional reactions that, if left unaddressed, erode the relationship from the inside. Naming these reactions can help partners separate the problem from the person.
- Shame and secrecy: One partner may hide purchases, accounts, or the true balance owed, fearing judgment from the other.
- Anxiety and sleeplessness: Constant worry about payments, collectors, and the future can make even small decisions feel overwhelming.
- Anger and blame: Frustration often lands on the spouse rather than on the system or the circumstances that created the debt.
- Hopelessness: When balances seem impossible to pay down, couples may stop planning for the future altogether.
- Isolation: Partners may withdraw emotionally or physically, believing they are protecting the other person from the truth.
These reactions are normal, but they are also dangerous when they become patterns. Shame leads to secrecy, secrecy leads to discovery, and discovery often leads to a crisis of trust that is harder to repair than the debt itself. Couples who understand this cycle early can interrupt it before it does lasting damage.
How Debt Changes Communication and Intimacy
Healthy marriages depend on open communication, and debt attacks that foundation directly. Couples in debt often stop talking about money because every conversation ends in conflict. They may agree to a truce, but the truce is really avoidance. Over time, the topics they avoid expand. They stop discussing vacations, home repairs, retirement, and even daily spending. The relationship becomes smaller and more guarded.
Intimacy suffers as well. Financial stress raises cortisol levels and disrupts sleep, which reduces patience and affection. Partners who feel judged about money may withdraw physically. Others may use sex or affection as a bargaining chip in financial disagreements. None of these patterns are inevitable, but they are common enough that couples should treat them as warning signs rather than personal failures.
The good news is that communication can be rebuilt. Couples who set aside regular, calm money conversations, ideally weekly and time-limited, often find that the fear of the conversation is worse than the conversation itself. When both partners agree that the goal is understanding rather than winning, the tone shifts from combat to collaboration.
Practical Coping Strategies That Strengthen the Marriage
Coping with the emotional impact of debt on marriage and how couples cope is not about pretending the stress does not exist. It is about building habits that keep the relationship stable while the financial situation improves. These strategies work best when both partners commit to them together, even if one partner is more financially literate or more motivated than the other.
- Create a judgment-free money meeting: Set a weekly 30-minute check-in with no blame and no surprises. Review balances, upcoming bills, and one shared goal.
- Separate the person from the problem: Agree that the debt is a shared enemy, not evidence of a spouse's character. Use language like "we are facing this" rather than "you did this."
- Build a small emergency buffer: Even $500 to $1,000 in savings reduces the panic that leads to new debt and new arguments.
- Seek outside support together: A nonprofit credit counselor, a financial therapist, or a structured debt relief program can provide neutral guidance and reduce the pressure on the marriage.
- Protect non-financial connection: Schedule time that has nothing to do with money. Walks, meals, and shared hobbies remind both partners why they chose each other.
These steps do not erase the debt, but they change the emotional climate. When couples feel like a team, they make better financial decisions and recover faster. When they feel like opponents, even a small setback can trigger a major relational crisis.
When Debt Relief Programs Become Part of the Solution
For many couples, the turning point comes when they realize that willpower alone will not solve a structural debt problem. High-interest credit card balances, medical bills, and personal loans can grow faster than any household budget can absorb. At that point, structured debt relief options deserve serious consideration. Debt settlement programs, for example, negotiate with creditors to reduce the total balance owed, often allowing clients to resolve unsecured debt for less than the full amount.
It is important to understand the trade-offs. Debt settlement can negatively affect credit scores in the short term, and forgiven debt may have tax implications. Couples should consult a qualified financial advisor and compare multiple options before committing. That said, for households facing genuine hardship, a structured program can replace months of anxiety with a clear plan and a defined timeline. Learning from real cases, such as breaking a debt settlement agreement, can help couples understand what happens if a plan is abandoned and why commitment matters.
Debtsend operates as a free matching service that connects individuals and couples with third-party partners who offer debt relief, consolidation, and reduction options. The process starts with a no-obligation assessment, takes only a few minutes, and does not by itself affect your credit. From there, couples can review personalized options and decide whether a structured program fits their situation. For spouses who feel trapped between bankruptcy and endless minimum payments, this kind of guided path can restore a sense of agency and hope.
Couples facing urgent cash-flow problems may also explore short-term personal loans as a bridge, though these should be used carefully and only when the math works. Services such as LendersCashLoan, a digital loan connection platform, help users submit a single request and compare potential offers from a network of third-party lenders, including options for applicants with less-than-perfect credit. Used responsibly, a short-term loan can prevent a crisis from snowballing, but it is not a substitute for a long-term debt strategy. Couples should treat any new borrowing as a temporary tool, not a permanent solution.
Rebuilding Trust After Financial Secrecy
When one spouse has hidden debt or spending, the damage is often more relational than financial. Rebuilding trust requires more than a budget. It requires transparency, consistency, and time. Couples who have experienced financial infidelity often benefit from a structured repair process that includes full disclosure of accounts and balances, shared access to financial statements, and regular check-ins that remove the opportunity for secrecy to return.
It also helps to separate forgiveness from consequences. A spouse can forgive the deception while still insisting on new financial safeguards. That balance prevents the relationship from becoming either punitive or naive. Many couples find that a written agreement, sometimes called a financial covenant, helps both partners feel protected and accountable. The agreement might specify spending limits, savings targets, and a commitment to discuss any new debt before it is opened.
The emotional impact of debt on marriage and how couples cope is ultimately a story about resilience. Debt can isolate partners, but it can also force them to build communication skills they never had. Couples who face the problem together often emerge with a stronger partnership than they had before the crisis, not because the debt was easy, but because they learned to trust each other under pressure.
Moving Forward as a Team
No couple plans to struggle with debt, and no couple deserves to feel ashamed for needing help. The path forward starts with honest conversation, a realistic plan, and the willingness to ask for support when the burden becomes too heavy to carry alone. Whether that support comes from a credit counselor, a debt settlement program, or simply a weekly meeting at the kitchen table, the goal is the same: to replace fear with a plan and isolation with partnership.
Couples who take that first step often discover that the debt was never the real enemy. The real enemy was silence. Once the silence breaks, the marriage has a chance to heal, and the finances have a chance to recover. If you are ready to explore your options, a free, no-obligation debt assessment can be the beginning of a calmer, more connected chapter for both of you.