How Debt Affects Mental Health and Sleep: Breaking the Cycle
Debt stress disrupts sleep and mental health, but the cycle can be broken. Learn how to reduce anxiety and rest better while tackling unsecured debt.
By Maribel Sloane
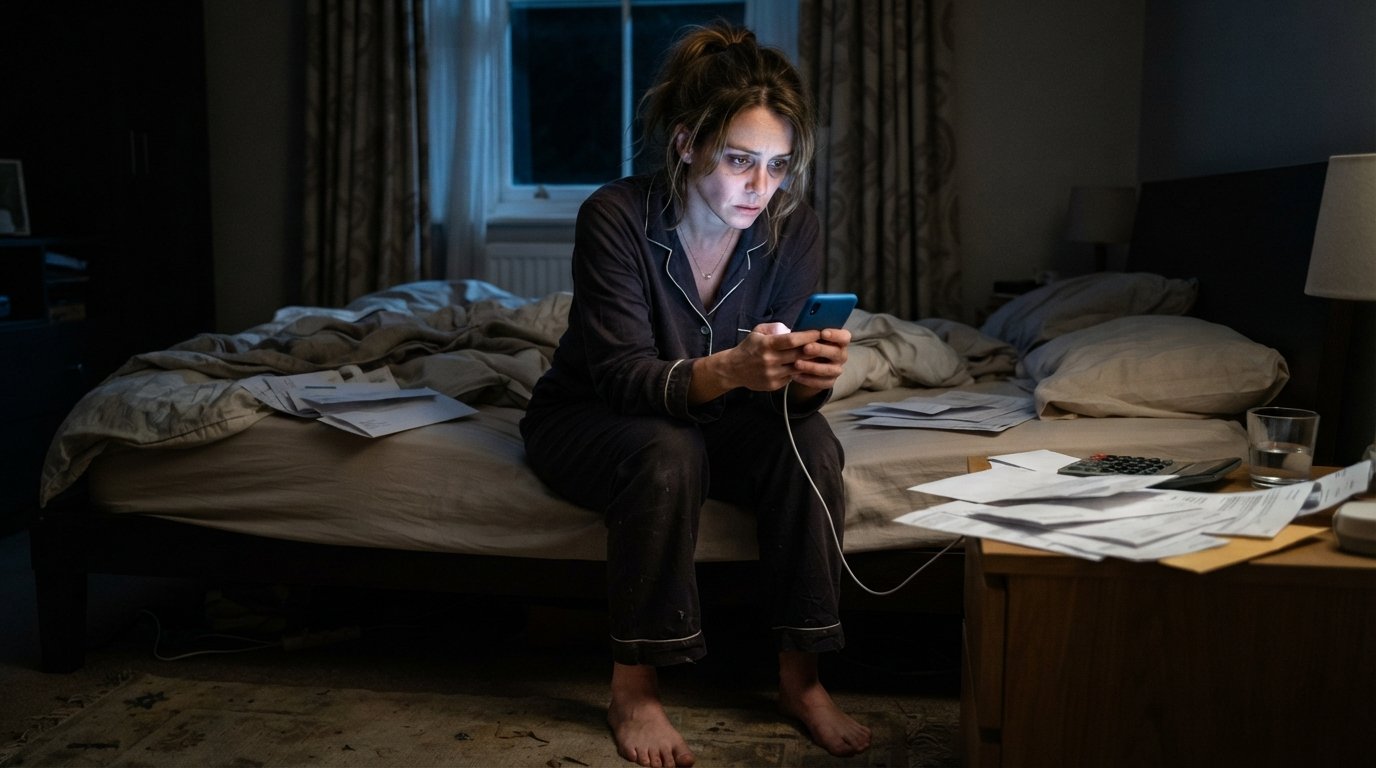
You know the feeling. It is 2:00 AM. You should be asleep, but your mind is running through a loop: the minimum payment due next week, the medical bill you cannot pay, the credit card balance that seems to grow no matter what you do. Your heart races. Your stomach knots. You check your banking app for the fifth time today, hoping the numbers have changed. They have not. This is not just a financial problem. It is a mental health problem, and it is a sleep problem. The three are tangled together in a cycle that can feel impossible to break.
Debt is one of the most common sources of chronic stress in the United States. According to the American Psychological Association, money is consistently ranked as a top stressor for adults, and for good reason. When you owe more than you can pay, the pressure does not stay in your bank account. It follows you to work, to family dinners, and to bed. It affects your mood, your focus, your relationships, and your ability to rest. Understanding how debt affects mental health and sleep is the first step toward taking back control. This article explains what happens in your brain and body when debt stress takes over, and it offers practical strategies to interrupt the cycle.
Why Debt Stress Feels Different From Other Stress
Not all stress is created equal. Acute stress, like a deadline at work or a traffic jam, is temporary. Your body surges with adrenaline and cortisol, you handle the problem, and your system returns to baseline. Debt stress is different because it is chronic. It does not go away when you finish a task. It is always there, waiting in the background, ready to flood your mind the moment you slow down.
Financial stress also carries a unique emotional weight. It is often tied to feelings of shame, failure, and helplessness. You may feel judged by others, or you may judge yourself. You might avoid opening bills or answering calls from collection agencies because the anxiety is too intense. This avoidance provides short-term relief but makes the problem worse over time. The debt grows, the calls continue, and the stress deepens.
Researchers have found that financial stress activates the same brain regions as physical threats. Your amygdala, the fear center of the brain, goes on high alert. Your prefrontal cortex, which handles logic and planning, becomes less effective. This is why you might make impulsive financial decisions when you are stressed, or why you might freeze and do nothing at all. Your brain is not broken. It is responding to a perceived threat, and for many people, debt feels like a threat to survival.
The Mental Health Toll of Persistent Debt
The link between debt and mental health is well-documented. Studies consistently show that people with high levels of unsecured debt, such as credit card balances, medical bills, and personal loans, are more likely to experience anxiety, depression, and insomnia. The relationship goes both ways: debt causes mental health struggles, and mental health struggles can make it harder to manage debt. It is a bidirectional cycle that can be difficult to escape without support.
Anxiety is the most immediate mental health effect. You may worry constantly about money, even when you are not actively dealing with it. You might feel a sense of dread when you check your mail or see a notification from your bank. This constant worry wears down your emotional reserves. Over time, it can lead to panic attacks, social withdrawal, and difficulty concentrating. You might find yourself snapping at loved ones or avoiding social events because you cannot afford to participate. The shame of debt can be isolating, and isolation makes everything worse.
Depression is another common outcome. When you feel trapped in a financial situation with no clear way out, hopelessness sets in. You might lose interest in activities you once enjoyed. You might feel fatigued, unmotivated, or unable to get out of bed. Debt can make you feel like a failure, and that feeling can seep into every area of your life. It affects your self-esteem, your relationships, and your sense of purpose.
The mental health impact of debt is not just about feelings. It has real consequences for your physical health as well. Chronic stress raises cortisol levels, which can lead to high blood pressure, heart disease, and a weakened immune system. People with high debt are more likely to report poor physical health, and they are more likely to delay medical care because they cannot afford it. This creates a vicious cycle where financial stress leads to health problems, which lead to more medical bills, which lead to more financial stress.
How Debt Disrupts Sleep
Sleep is often the first casualty of financial stress. When you are worried about money, your brain does not want to shut down. It wants to solve the problem. This is why so many people lie awake at night, replaying financial scenarios in their heads. The quiet of the night, when there are no distractions, is when the worry is loudest.
Debt-related sleep problems can take several forms. You might have trouble falling asleep because your mind is racing. You might wake up in the middle of the night with a knot in your stomach, unable to fall back asleep. You might sleep restlessly, tossing and turning, and wake up feeling exhausted. Some people sleep too much, using sleep as an escape from their financial reality. Others develop insomnia that persists even when they are not actively thinking about money.
The science behind this is clear. Stress activates the sympathetic nervous system, which is your body's fight-or-flight response. This response is designed to keep you alert and ready to respond to danger. It is not designed to help you sleep. When your sympathetic nervous system is constantly activated by debt stress, your body never gets the signal that it is safe to rest. Your cortisol levels stay elevated, your heart rate stays up, and your brain stays on high alert.
Poor sleep, in turn, makes everything worse. When you do not sleep well, your mood suffers. You are more irritable, more anxious, and more depressed. Your cognitive function declines, making it harder to focus, make decisions, and solve problems. Your impulse control weakens, which can lead to poor financial choices. And your physical health suffers, which can lead to more medical bills. The lack of sleep becomes both a symptom of debt stress and a cause of it.
Recognizing the Warning Signs
If you are struggling with debt, it is important to recognize how it is affecting your mental health and sleep. The signs are not always obvious, especially if you have been living with them for a while. Here are some common warning signs to watch for:
- Persistent anxiety or worry about money that interferes with daily life
- Difficulty falling asleep or staying asleep because of financial thoughts
- Feeling hopeless or depressed about your financial situation
- Avoiding opening bills, checking bank accounts, or answering calls from creditors
- Physical symptoms such as headaches, stomach problems, or muscle tension
- Withdrawing from friends and family because of shame or lack of money
- Irritability or mood swings that seem out of character
- Fatigue that does not improve with rest
If you recognize yourself in these signs, you are not alone. Millions of Americans are in the same situation. Recognizing the problem is the first step toward addressing it. The next step is to find support and take action.
Breaking the Cycle: Practical Strategies for Relief
The good news is that the cycle of debt, mental health struggles, and poor sleep can be broken. It takes time and effort, but it is possible. The key is to address both the financial and emotional sides of the problem. Trying to fix one without the other rarely works.
Start by acknowledging the emotional toll. It is okay to feel stressed, anxious, or depressed about debt. These are normal reactions to an abnormal situation. Give yourself permission to feel what you feel without judgment. Then, take a small step toward action. Even a small step can reduce anxiety because it gives you a sense of control.
One of the most effective things you can do is create a clear picture of your financial situation. Avoidance fuels anxiety. When you know exactly how much you owe, to whom, and at what interest rates, the problem becomes concrete. It might be scary, but it is manageable. Make a list of all your debts, including balances, minimum payments, and due dates. Then, look at your income and expenses. Are there any areas where you can cut back? Are there any debts you can consolidate or negotiate?
If your unsecured debt feels overwhelming, you might consider a structured debt relief program. Companies like LendersCashLoan connect people with financial hardship to potential lending partners who may offer short-term personal loans or debt consolidation options. These can provide breathing room by simplifying payments or reducing interest rates. For those with significant unsecured debt, debt settlement programs, like those offered through Debtsend's matching service, can negotiate with creditors to reduce the total amount owed. This can provide a clear path to becoming debt-free, which in turn reduces stress and improves sleep.
It is important to note that debt settlement is not right for everyone. It can have a negative impact on your credit score and may have tax implications. However, for people facing genuine hardship who have explored other options, it can be a lifeline. It is always wise to consult with a qualified financial advisor and compare multiple options before making a decision.
In addition to financial strategies, you need strategies for managing stress and improving sleep. These are not luxuries; they are essential for your overall health and your ability to make good financial decisions. Here are some steps you can take:
- Create a worry time. Set aside 15 minutes each day to worry about money. Write down your concerns. When the time is up, close the notebook and move on. This can help contain anxiety so it does not spill into every hour of the day.
- Practice relaxation techniques. Deep breathing, meditation, and progressive muscle relaxation can calm your nervous system. Even a few minutes a day can make a difference.
- Establish a sleep routine. Go to bed and wake up at the same time every day. Avoid screens for an hour before bed. Create a cool, dark, quiet sleep environment. If you wake up in the middle of the night, do not lie there worrying. Get up, do something calming, and return to bed when you feel sleepy.
- Seek support. Talk to a trusted friend, family member, or therapist. You do not have to go through this alone. Support groups for people with financial stress can also be helpful.
- Take care of your physical health. Exercise, eat well, and limit caffeine and alcohol. These habits improve both your mental health and your sleep.
These strategies are not a cure-all, but they can help you regain a sense of control. When you feel more in control, your anxiety decreases, and your sleep improves.
When to Seek Professional Help
If your debt stress is severe, or if you are experiencing symptoms of depression or anxiety that interfere with your daily life, it is important to seek professional help. A mental health professional can help you develop coping strategies and, if necessary, prescribe medication. A financial counselor can help you create a plan to manage your debt. You do not have to figure everything out on your own.
Debtsend offers a free, no-obligation debt assessment that can connect you with personalized options in minutes. Their service is designed to be compassionate and judgment-free. They understand that financial hardship can happen to anyone, and they are there to help you find a way forward. Taking that first step can be scary, but it can also be the moment when things start to change.
Remember that debt is not a moral failing. It is a circumstance. It does not define who you are, and it does not have to define your future. With the right support and strategies, you can reduce your debt, improve your mental health, and sleep better at night. The cycle can be broken. You just have to start.