How to Handle Debt Collector Calls at Work
Handle debt collector calls at work with confidence using boundary scripts, legal rights, and a simple plan to protect your job and resolve debt.
By Calvin Brooks
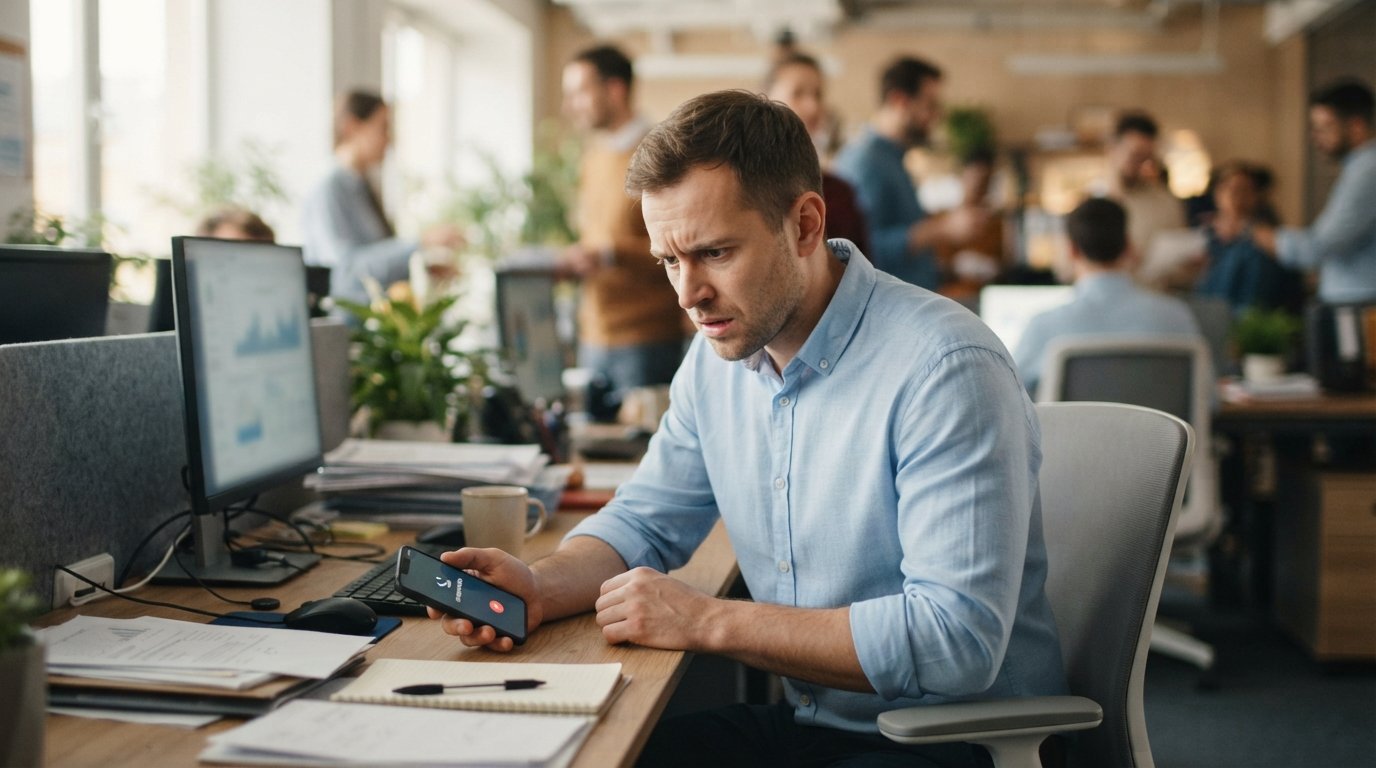
The phone buzzes on your desk, and the caller ID shows a number you do not recognize. You let it go to voicemail, but the pit in your stomach tells you it is probably another debt collector. When you are on the clock, a call like that can feel like a trap: answer it and risk a tense conversation in front of coworkers, or ignore it and spend the rest of the day anxious about what comes next. If this scene feels familiar, you are not alone. Thousands of people juggle unsecured debt, including credit cards, personal loans, and medical bills, while trying to hold down a job and keep their finances private. The good news is that you have more control over workday collection calls than you might think, and a clear plan can protect both your paycheck and your peace of mind.
Know What Debt Collectors Can and Cannot Do at Work
Before you decide how to respond, it helps to understand the rules collectors have to follow. Under the Fair Debt Collection Practices Act (FDCPA), a third-party collector generally cannot call you at work if they know your employer prohibits it. That protection is not automatic, though. It activates once you tell the collector that your workplace does not allow personal calls, and you can make that request by phone or in writing. Once you do, the collector should stop calling your job.
Even so, some calls slip through. A collector may not know your workplace policy, may have an old number, or may be calling from a first-party creditor that is not covered by the same rules. Understanding the difference between your rights and real-world behavior keeps you prepared. If you want a deeper look at the legal boundaries, our guide on whether debt collectors can call your employer explains when those calls cross the line and what you can do about it.
It also helps to know that collectors are trained to reach you wherever you are most likely to pick up. Your workplace is often that place. That does not mean you have to engage on their schedule. It means you need a strategy that fits your workday, your privacy, and your long-term plan for resolving the debt.
Set Clear Boundaries Without Escalating the Call
The first few moments of a collection call usually set the tone. If you answer at work, keep your voice calm and your answers short. You do not need to explain your situation, defend your past choices, or promise a payment you cannot make. You simply need to establish what is acceptable and what is not.
Here is a simple boundary script you can adapt: "I am at work and cannot discuss this now. Please do not call me here again. You can reach me by mail, or I will call you back on my break." Then end the call politely. If the collector pushes, repeat the same sentence once and hang up. You are not being rude; you are protecting your job and your right to handle the debt on your own terms.
Putting your request in writing strengthens your position. Send a brief letter or email that states your employer does not permit personal calls and that you want all future communication in writing. Keep a copy and note the date you sent it. If calls continue, you have a record that can support a complaint to the Consumer Financial Protection Bureau or your state attorney general.
You can also use a few practical tools to reduce workday interruptions:
- Save collector numbers in your phone so you know not to answer during work hours.
- Turn on Do Not Disturb during meetings and let unknown callers go to voicemail.
- Create a dedicated email address for debt-related correspondence.
- Ask your HR department about workplace policies on personal calls, so you can cite them if needed.
These steps are not about avoiding your debt. They are about creating a calm, private space to deal with it. When you are not caught off guard, you make better decisions about payments, settlements, and next steps.
Create a Workday Communication Plan
A little planning goes a long way. Instead of reacting to every call, decide in advance how and when you will communicate with collectors. Many people find that a single 15-minute block during lunch or after work is enough to return calls, check mail, and update their notes. That way, debt conversations do not bleed into your work hours or your evenings.
Your plan can include a simple log that tracks each call: the date, the collector's name, the company, what was said, and any agreements. This record is useful if you later dispute a debt, negotiate a settlement, or need to prove that you asked for calls to stop. It also gives you a sense of progress, which can reduce the feeling that you are being chased with no end in sight.
If your debt has grown beyond what you can manage on your own, it may be time to explore structured relief options. A free debt assessment can show you what a debt settlement program might look like for your situation, including one monthly payment and the possibility of reduced balances. Platforms such as FreeQuotes.Loans let you compare personalized loan offers from a network of lenders, which can be helpful if you need to consolidate or cover an urgent expense while you work on a longer-term plan.
For those with significant unsecured debt, a matching service like Debtsend can connect you with partners who negotiate with creditors on your behalf. The process is designed to be simple: you complete a short evaluation, get matched with options, and choose a path that fits your budget. You can start by using the Estimate Savings tool to see potential outcomes before you commit to anything.
Protect Your Job and Your Privacy
Your employer does not need to know about your debt, and you are not obligated to share details with coworkers or managers. If a collector reaches a workplace line or a colleague, you can simply say, "Please do not call me here. This is a personal matter." You do not have to confirm that you owe the debt or discuss any account details with anyone who is not authorized.
In rare cases, a collector may contact your employer to verify employment or locate you. They generally cannot disclose that you owe a debt to your employer or coworkers. If someone at work tells you a collector shared personal information, document what happened and consider filing a complaint. The FDCPA prohibits third-party disclosure of your debt to people who do not have a legitimate need to know.
It is also wise to keep your personal phone and email separate from work devices. Use your own phone for collection calls, and avoid logging into personal financial accounts on a work computer if your employer monitors usage. These small habits keep your financial life private and reduce the chance that a workday call turns into an awkward conversation with your boss.
Decide When to Negotiate, Settle, or Seek Help
Handling calls is only half the battle. At some point, you have to decide how you will resolve the debt itself. If you can afford to pay in full, you may be able to set up a payment plan directly with the creditor. If the balance is too high, you might negotiate a lower lump-sum settlement. If you have multiple accounts and feel overwhelmed, a structured debt relief program could consolidate the process into one monthly payment.
Here is a simple framework to help you choose:
- List all your unsecured debts, including balances, interest rates, and minimum payments.
- Calculate how much you can realistically put toward debt each month without missing essential bills.
- Contact creditors or a reputable debt relief partner to discuss settlement, consolidation, or a payment plan.
- Get any agreement in writing before you make a payment.
- Review the impact on your credit score and any potential tax consequences of forgiven debt.
Debt settlement can reduce what you owe, but it is not right for everyone. It may affect your credit score, and forgiven debt over $600 can be taxable. That is why it is important to compare options and speak with a qualified financial advisor or tax professional before you commit. A reputable matching service will explain these trade-offs clearly and help you understand what to expect.
If you are facing genuine hardship and have already explored other alternatives, a program that negotiates with creditors may offer a path forward. The key is to act before the stress of collection calls starts affecting your work performance or your health. When you have a plan, a call at work becomes a minor interruption instead of a crisis.
Take Control of the Next Call
The next time your phone rings at work, you can answer with confidence or let it go to voicemail without guilt. You know your rights, you have a script, and you have a plan for resolving the debt on your own timeline. Start by documenting your accounts, setting boundaries with collectors, and exploring relief options that fit your budget. Whether you negotiate directly, use a matching service, or simply request that calls stop, you are moving toward financial freedom one step at a time. The stress does not have to follow you to your desk.