
How to Stop Using Credit Cards While Paying Off Debt
Need a plan for how to stop using credit cards while paying off debt? Call 8336708023 for a free, no-obligation debt assessment and personalized options.
By Violeta Cruz
You have made the decision to pay off your credit card debt. You have created a budget, identified the balances you want to eliminate, and maybe even set up a plan to make extra payments each month. There is just one problem: the cards are still in your wallet, and the temptation to use them is real. For many people, the hardest part of debt repayment is not finding the money to pay, it is changing the daily habit of swiping a card when cash is tight or a surprise expense appears. Learning how to stop using credit cards while paying off debt is a skill, not just a decision, and it requires practical strategies that address both the financial and psychological sides of spending.
The stakes are high. Every new charge adds to the balance you are trying to eliminate, increases the interest you owe, and extends the time it takes to become debt-free. If you are working with a debt settlement program or considering one, new credit card activity can also complicate the negotiation process. Lenders and creditors want to see that you are committed to resolving your debt, and continued card use can undermine that message. The good news is that stopping is possible with the right approach, and you do not have to rely on willpower alone.
Why Willpower Alone Rarely Works
Many people believe that if they simply want to stop using credit cards badly enough, they will. This belief sets them up for failure. Credit cards are designed to be convenient, and years of habitual use have wired your brain to reach for a card in certain situations. Stress, unexpected bills, and even everyday purchases like groceries can trigger automatic card use before you have time to think about it. Understanding this can help you stop blaming yourself and start building systems that make card use harder.
Behavioral research shows that changing your environment is far more effective than relying on self-control. If your credit card is saved in an online shopping account, you are more likely to use it. If it is in your wallet next to your ID, you will see it every time you open your wallet. The goal is to create friction, small obstacles that give your brain time to choose a different action. When you make card use inconvenient, you give yourself a chance to pause, think, and choose a payment method that does not add to your debt.
Another reason willpower fails is that it is finite. You can resist temptation for a while, but by the end of a long day, your resolve is depleted. This is why late-night online shopping and impulse purchases are so common. Building a system that protects you when your willpower is low is far more reliable than trying to power through on determination alone.
Practical Steps to Stop Using Credit Cards
The following steps are not just about removing cards from your life. They are about replacing the function credit cards served with healthier alternatives and creating a financial environment that supports your debt payoff goals. You do not have to do all of these at once, but the more you implement, the easier it will become to stop using credit cards while paying off debt.
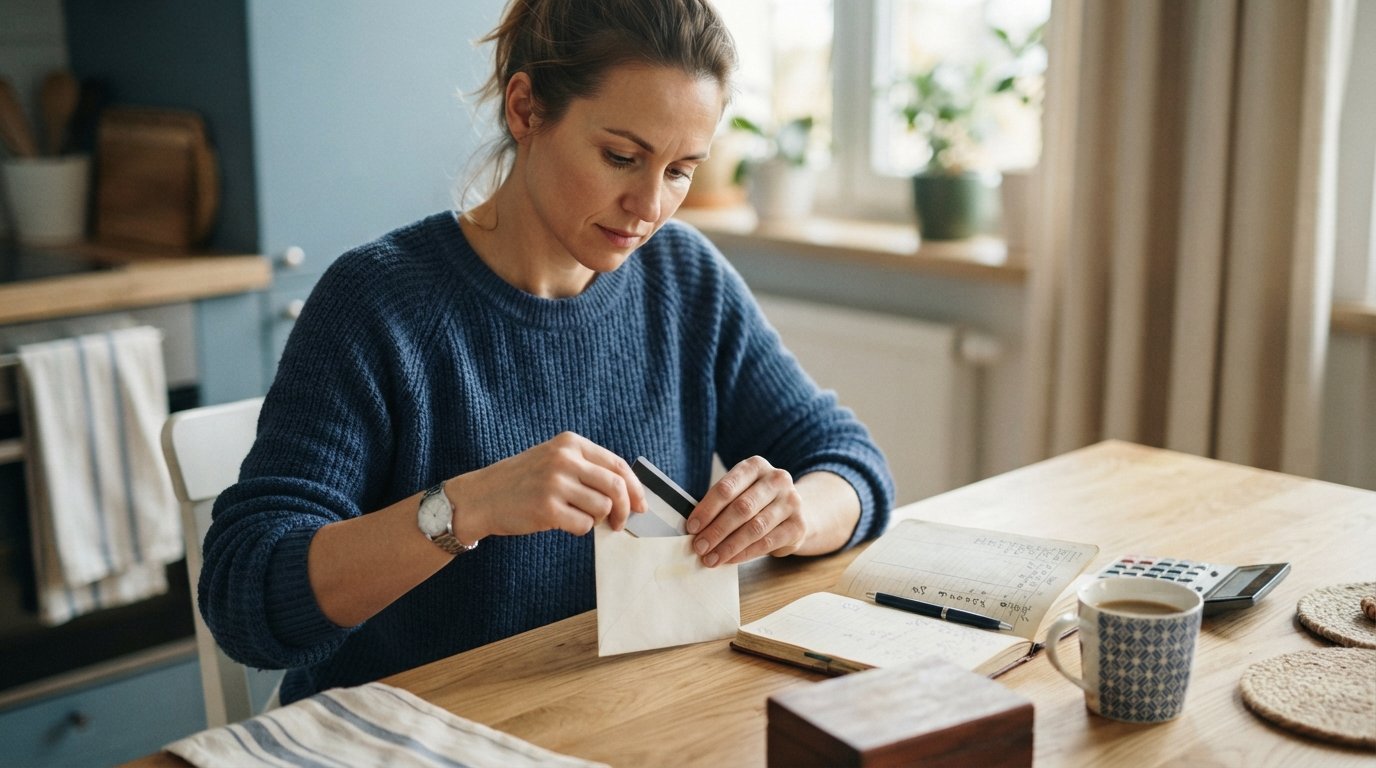
- Remove cards from your wallet and digital wallets. Take the physical cards out of your wallet and store them in a safe place at home, such as a locked drawer or a safe. Remove them from your phone's digital wallet, your browser's autofill, and any shopping apps where they are saved. This single action can dramatically reduce impulse spending.
- Switch to cash or a debit card for daily spending. A debit card withdraws money directly from your checking account, so you cannot spend more than you have. Cash works even better for discretionary spending because once it is gone, it is gone. Many people find that paying with cash makes them more aware of how much they are spending.
- Create a realistic budget that accounts for irregular expenses. One of the main reasons people reach for credit cards is that they have not planned for car repairs, medical bills, or annual expenses. A budget that includes a sinking fund for these costs reduces the need to rely on credit.
- Set up automatic payments for bills from your checking account. If you are used to paying recurring bills with a credit card, switch those payments to your debit card or bank account. This ensures you do not accidentally add to your credit card balance.
- Tell someone about your goal. Accountability can be powerful. Share your commitment to stop using credit cards with a trusted friend or family member. Knowing that someone will check in on your progress can help you stay on track.
These steps work best when combined. Removing cards from your wallet is a good start, but if you have not addressed the underlying reasons you were using them, you may find yourself digging them out again. A budget that accounts for irregular expenses and a clear plan for how you will pay for things without credit are essential. If you are working with a debt settlement company, let them know about your efforts. Many programs, including those facilitated through Debtsend, encourage clients to stop using credit cards during the negotiation process.
Dealing With the Urge to Spend
Even with cards out of reach, the urge to spend can be strong. You might see a sale, feel stressed, or want to treat yourself after a difficult week. These urges are normal, but you can learn to manage them without turning to credit. One effective technique is the 24-hour rule. When you feel the urge to buy something non-essential, write it down and wait 24 hours. If you still want it after a day, you can consider buying it with cash or your debit card. Often, the urge passes.
Another strategy is to identify your spending triggers. Do you spend more when you are bored, stressed, or lonely? Once you recognize the pattern, you can find alternative ways to address those feelings. Going for a walk, calling a friend, or working on a hobby can fill the same need without adding to your debt. For some people, tracking their spending for a few weeks reveals surprising patterns and helps them make lasting changes.
If you find that you are struggling with compulsive spending, it may be worth talking to a financial counselor or therapist who specializes in money behaviors. This is not a sign of weakness, it is a smart step toward lasting financial health. The emotional toll of debt is real, and addressing it can make the practical steps of repayment much easier to sustain.
What to Do When You Have No Other Option
There will be times when you genuinely need to make a purchase and you do not have enough cash or debit funds available. This is where planning ahead matters. If you know a large expense is coming, such as a car repair or a medical bill, start saving for it now. Even setting aside a small amount each week can help. If the expense is truly unexpected and you cannot cover it, you may need to consider alternatives such as a payment plan with the service provider or a short-term loan. Platforms like ExpressCash connect consumers with lenders who offer short-term loan options, which can be a temporary solution for those facing unexpected expenses. However, it is important to use these options sparingly and have a plan to repay them, as they can become another source of financial stress if not managed carefully.
If your debt feels overwhelming and you are struggling to make progress, you may want to explore debt relief options. Debt settlement programs can negotiate with creditors to reduce the total amount you owe, often allowing you to resolve your debt for less than the full balance. Companies like Debtsend help individuals connect with partners who offer these services. The process typically involves setting aside money in a dedicated account and making one monthly payment, which is used to fund settlements as they are reached. It is important to understand that debt settlement can have a negative impact on your credit score and may have tax implications, so it is wise to consult with a financial advisor before committing.
If you are dealing with high-interest credit card debt, you might be wondering if there is a way to stop the interest from accruing while you work on repayment. In our guide on stopping credit card interest legally, we explain the options that may be available to you. Understanding these options can help you make informed decisions about the best path forward for your situation.
Building a Support System
You do not have to go through this alone. Whether you are paying off debt on your own or working with a debt relief company, having support makes a difference. Consider joining a support group, either in person or online, where you can share challenges and celebrate victories with others who understand what you are going through. Many people find that the encouragement and accountability they receive from a community helps them stay committed to their goals.
If you are married or have a partner, it is especially important to get them on board with your plan to stop using credit cards. Financial disagreements can strain relationships, but working together toward a shared goal can bring you closer. Have honest conversations about your spending, your debt, and your plan to become debt-free. You may need to make compromises, such as agreeing on a weekly cash allowance for discretionary spending, but the effort is worth it.
Professional support is also available. Nonprofit credit counseling agencies can help you create a budget, understand your options, and develop a plan to pay off debt. If you are considering debt settlement, companies like Debtsend can connect you with partners who specialize in negotiating with creditors. The key is to do your research, ask questions, and choose the path that aligns with your values and financial situation.
Staying Motivated for the Long Haul
Paying off debt is a marathon, not a sprint. There will be months when progress feels slow, and you may be tempted to give up. Staying motivated requires reminding yourself why you started. What will your life look like when you are debt-free? Maybe you will have more financial flexibility, less stress, or the ability to save for something you have always wanted. Write down your reasons and keep them somewhere you can see them.
Celebrate milestones along the way. When you pay off a card, reduce your balance by a certain amount, or go a month without using credit, reward yourself in a way that does not involve spending money. Acknowledge your progress and give yourself credit for the hard work you are doing. It is easy to focus on what is left to pay, but recognizing how far you have come can fuel your motivation to keep going.
Finally, be patient with yourself. Changing your relationship with credit takes time. There may be setbacks, and that is okay. What matters is that you keep moving forward. If you slip up and use a credit card, do not abandon your plan. Instead, figure out what happened, adjust your approach, and get back on track. Every step you take toward reducing your debt is a step toward financial freedom.
Stopping the use of credit cards while paying off debt is challenging, but it is absolutely possible. By removing temptation, creating a realistic budget, finding healthy alternatives for spending triggers, and building a support system, you can break the cycle and make real progress. Whether you are paying off debt on your own or working with a debt relief program, the commitment you make today can change your financial future. Reach out to a trusted financial professional or a service like Debtsend to explore your options and take the next step toward a debt-free life.