
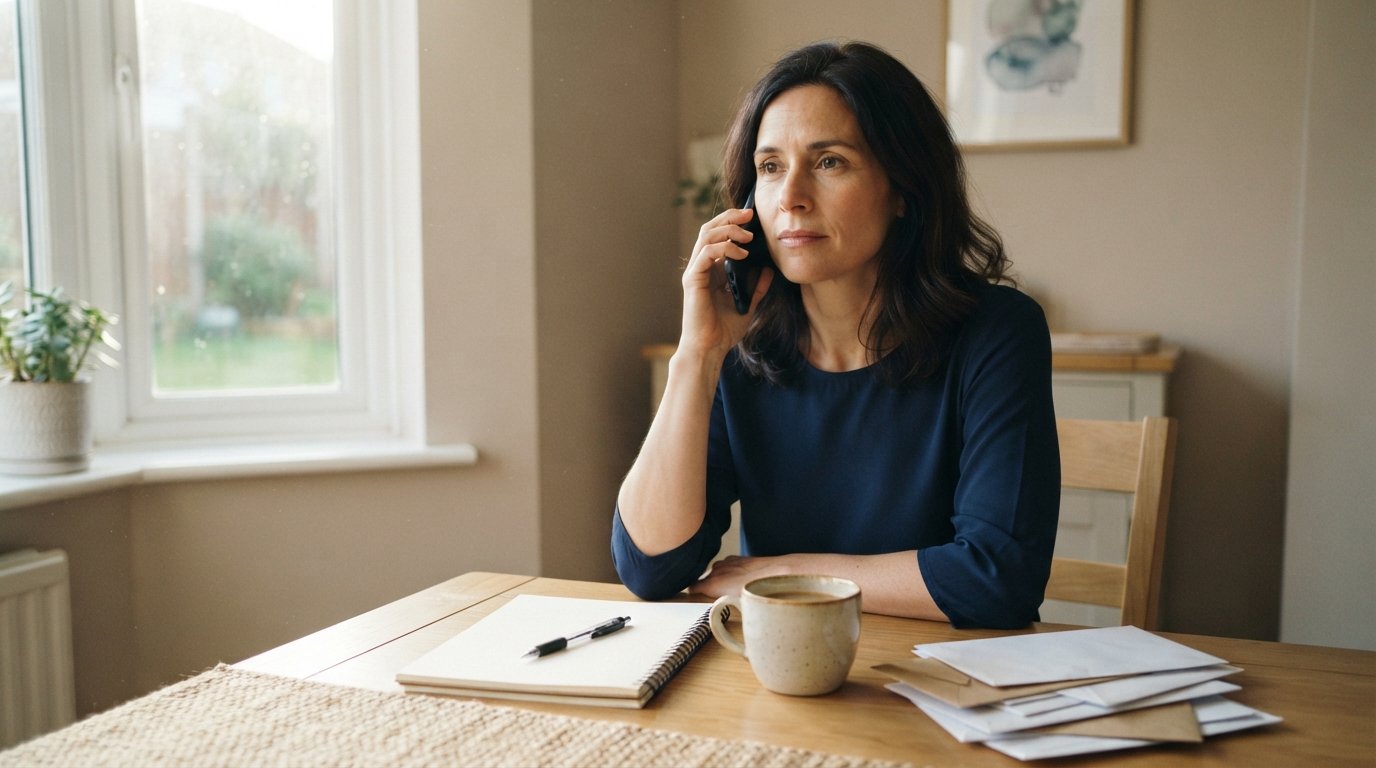
How to Talk to a Debt Collector Without Losing Your Cool
Stay calm and in control when debt collectors call. Learn how to talk to a debt collector without losing your cool and protect your rights. Call 8336708023 for help.
By Maribel Sloane
The phone rings, and you recognize the number. Your stomach tightens. It is a debt collector, and just the sound of their voice can make your pulse race. You are not alone. Millions of Americans face collection calls every day, and the stress can feel overwhelming. But here is the truth: you have more power in these conversations than you think. Knowing how to talk to a debt collector without losing your cool is not about becoming a pushover or a bulldozer. It is about staying calm, protecting your rights, and steering the conversation toward a resolution that works for you. Whether you are dealing with credit card debt, medical bills, or personal loans, the strategies in this guide will help you keep your composure and your leverage.
Why Debt Collectors Call and What They Really Want
Before you can master the art of the calm conversation, it helps to understand the other side. Debt collectors are not calling to ruin your day. They are calling because they are paid to recover money. Some work for the original creditor, while others are third-party agencies that have purchased your debt for pennies on the dollar. Their goal is simple: get you to pay something, often as much as possible, as quickly as possible.
But here is what they do not want you to know: they are used to people who yell, hang up, or make empty promises. When you stay calm and informed, you become a different kind of caller, one who is harder to intimidate and more likely to get a fair deal. Collectors are trained to push emotional buttons. They might imply you will be sued, threaten to call your employer, or shame you for not paying. Recognizing these tactics as scripted moves, not personal attacks, is your first step toward keeping your cool.
It is also important to know your rights under the Fair Debt Collection Practices Act (FDCPA). This federal law prohibits collectors from calling before 8 a.m. or after 9 p.m., harassing you, making false threats, or contacting you at work if you have told them not to. When you know the rules, you can respond with confidence instead of fear. For example, if a collector threatens to have you arrested, you can calmly say, "I know that is not legal, and I am recording this call." That simple statement often changes the tone immediately.
Before You Dial or Answer: Preparation Is Your Armor
You would not walk into a courtroom without preparing, and you should not handle a debt collection call without a plan. Preparation is the best way to keep your emotions in check. Start by gathering key documents: your credit report, any letters from the collector, and a log of previous communications. Know exactly what debt they are talking about, the original creditor, the amount, and whether it is within the statute of limitations for collection in your state.
Next, set up a dedicated space for the call. Find a quiet room where you will not be interrupted. Have a pen and paper ready, or a notes app on your phone. You will want to record the date, time, the collector's name, the agency name, and what was said. This record can be invaluable if you later need to file a complaint or dispute a charge.
Finally, decide on your goal for the conversation. Are you trying to negotiate a lower payoff, set up a payment plan, or simply verify the debt? Write down your goal and a few key phrases you can fall back on if you start to feel flustered. For example: "I am not able to pay that amount today, but I want to resolve this. What options do you have?" Having a script keeps you from reacting on impulse. If you are also dealing with employer calls, our guide on can debt collectors call your employer legally can help you set boundaries at work.
During the Call: Techniques to Stay Calm and in Control
The moment the call connects, your body may tense up. That is normal. The key is to slow everything down. Take a deep breath before you speak. Let the collector talk first, and listen carefully. You do not have to respond immediately. A pause of two or three seconds can feel like an eternity, but it gives you time to think and signals that you are not easily rattled.
Use a calm, neutral tone. Speak slightly slower than you normally would. If the collector interrupts or raises their voice, do not match their energy. Instead, say, "I need you to stop interrupting me. I am trying to work with you." If they continue, you can say, "I am going to end this call now. Please send me everything in writing." Then hang up. You are not being rude; you are enforcing a boundary.
One of the most powerful phrases you can use is, "I am not admitting this debt. I am requesting validation." Under the FDCPA, you have the right to ask the collector to verify the debt in writing. Until they do, they must stop collection efforts. This simple request shifts the power dynamic. It also gives you time to research and decide on your next step without pressure.
Here are five phrases that can help you stay cool and in control during a tense call:
- "I am recording this call for my records." (This often makes collectors more cautious.)
- "Please send me a written validation of this debt."
- "I cannot pay that amount, but I can afford $X per month."
- "I am not able to discuss this right now. Please contact me by mail only."
- "I know my rights under the FDCPA, and I will report any violations."
After you use one of these phrases, follow it with a question. For example: "Can you confirm the original creditor and the date of last activity?" Asking questions keeps the collector on their toes and gives you more information to work with. It also prevents you from getting stuck in a defensive posture.
Negotiating Without Emotion: How to Talk Numbers
Once you have established a calm tone and validated the debt, you can move toward negotiation. This is where many people lose their cool because they feel desperate or ashamed. Remember, negotiation is a business conversation. The collector wants money; you want a reasonable resolution. Your goal is to find a middle ground.
Start by asking what options are available. Collectors often have authority to settle for less than the full balance, especially if the debt is old or if you can pay a lump sum. If you can afford a one-time payment, offer a percentage, such as 40% or 50% of the total. If you need a payment plan, propose an amount that fits your budget, not what the collector demands. Do not agree to anything you cannot sustain. A broken promise will only lead to more calls and less trust.
It is also wise to get any agreement in writing before you pay a dime. Ask the collector to send you a letter outlining the settled amount, the due date, and a statement that the remaining balance will be forgiven. This protects you from later surprises. If the collector refuses, that is a red flag. You can say, "I am happy to resolve this, but I need written confirmation first. Please send it to my address."
If you are dealing with multiple debts and feel overwhelmed, a structured debt settlement program might be a better path than negotiating each call alone. Companies like LendersCashLoan connect consumers with potential loan offers, but for debt relief specifically, a matching service like Debtsend can help you explore settlement options with vetted partners. The key is to avoid making emotional decisions. Stick to your budget and your plan.
When the Conversation Goes Wrong: Handling Threats and Harassment
Even with the best preparation, some calls go sideways. A collector might threaten you, use profane language, or call repeatedly. If this happens, you do not have to endure it. The FDCPA gives you the right to demand that they stop contacting you. You can say, "I am invoking my right to cease communication. Do not call me again. All future contact must be in writing." Once you make this request verbally, follow up with a written letter sent via certified mail. Keep a copy for your records.
If the harassment continues, you can file a complaint with the Consumer Financial Protection Bureau (CFPB) or your state attorney general. You can also sue a collector in civil court for violations, and you may be awarded damages. Knowing these remedies can give you a sense of control, which in turn helps you stay calm.
Another common scenario is the collector claiming they will sue you. Do not panic. Ask for the name of the attorney or the court where the lawsuit will be filed. Many threats are empty. If a lawsuit is real, you will receive a formal notice. In the meantime, you can consult a consumer law attorney or a reputable debt relief company to understand your options. If you are in California, for example, you might seek California debt help resources that specialize in consumer protection.
After the Call: Next Steps to Protect Yourself
Once you hang up, do not just move on. Take a few minutes to document everything. Write down what was said, who you spoke with, and any agreements made. If you promised a payment, mark the date on your calendar. If you requested validation, note the deadline for their response. This record will help you stay organized and avoid duplicate calls.
If you agreed to a settlement or payment plan, make sure you receive the written confirmation before sending money. Pay with a method that provides a receipt, such as a money order or a bank check, and never give a collector direct access to your bank account unless you have a trusted, long-term agreement. Once the debt is settled, keep the confirmation letter indefinitely. You may need it if the debt is later sold or reported incorrectly.
Finally, consider the bigger picture. One collection call is just a moment in your financial journey. If you are facing overwhelming unsecured debt, you might benefit from a comprehensive solution. Debt settlement programs, for example, negotiate with creditors to reduce what you owe, often allowing you to pay a fraction of the balance over time. These programs are not right for everyone, and they can impact your credit score and have tax implications, so it is important to speak with a qualified financial advisor and compare multiple options. A free debt assessment with a matching service like Debtsend can help you see what you qualify for without any obligation.
Building Long-Term Resilience Against Debt Stress
Learning how to talk to a debt collector without losing your cool is a skill that extends beyond one phone call. It is about reclaiming your power in a situation that often feels powerless. Each time you stay calm, you build confidence. Each time you assert your rights, you remind yourself that you are not a victim. You are a person navigating a difficult circumstance with dignity.
To strengthen your resilience, focus on what you can control: your budget, your communication, and your plan. Avoid isolating yourself. Talk to a trusted friend, join a support group, or seek financial counseling. Many nonprofit credit counseling agencies offer free or low-cost sessions. They can help you create a budget, understand your options, and even negotiate with creditors on your behalf.
Remember that debt does not define you. It is a financial situation, not a character flaw. The collectors on the other end of the line are doing a job, but you are the one with the power to decide how you respond. With the right mindset and the strategies in this guide, you can handle any collection call with composure and clarity. And if you need a structured path forward, consider reaching out to a reputable debt relief program that can help you end the stress and find your freedom.