How to Tell Your Family About Debt Problems
Telling your family about debt problems can feel overwhelming, but honesty can bring relief and support. Learn how to start the conversation with confidence.
By Elowen Hart
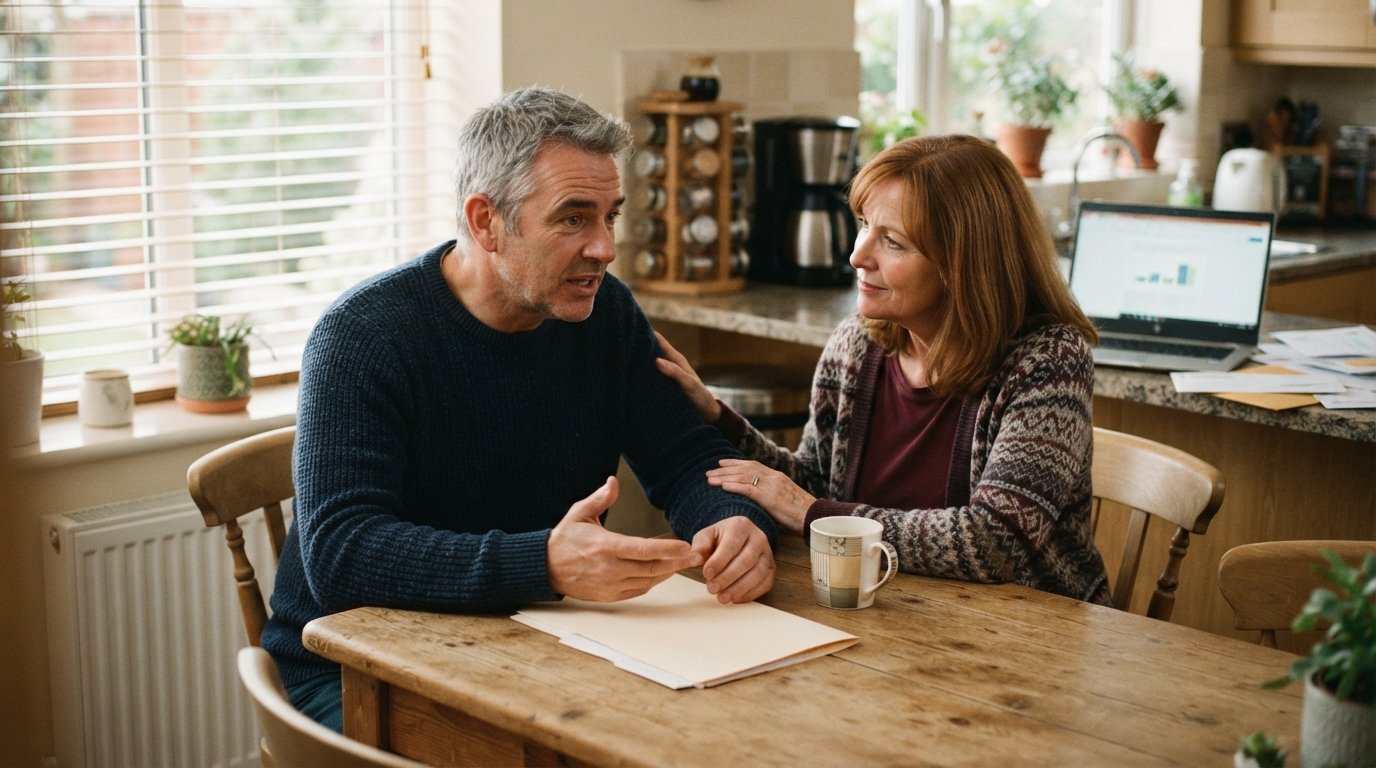
You have been carrying the weight of your debt alone, hiding statements, avoiding calls, and feeling a knot in your stomach every time the topic of money comes up. The thought of telling your family about your debt problems can feel terrifying. You might fear judgment, disappointment, or becoming a burden. But secrecy often makes financial stress worse, isolating you when you need support the most. Opening up is a crucial step toward relief, and it can be done in a way that protects your relationships and your peace of mind. This guide will walk you through how to tell your family about debt problems with honesty, preparation, and a plan for moving forward.
Why Telling Your Family Matters
Debt thrives in the dark. When you keep financial struggles hidden, you add shame and anxiety to an already heavy load. Research shows that financial stress can affect mental health, relationships, and even physical well-being. By sharing your situation, you release some of that pressure and create an opportunity for your loved ones to support you, whether emotionally or practically. Moreover, family members may inadvertently contribute to the problem if they are unaware, for example, by expecting you to participate in expensive activities or by making financial decisions that assume you are debt-free. Being open allows everyone to adjust expectations and work together.
However, telling your family is not just about unloading your burden. It is also about respecting their role in your life and giving them the chance to help. Many people find that their families are more understanding than they feared. The conversation can strengthen trust and bring you closer. That said, you should approach it thoughtfully, as money can be a sensitive topic. The goal is not to ask for a bailout, but to be honest about your situation and, if appropriate, to share your plan for resolving it.
Preparing for the Conversation
Before you sit down with your family, take time to prepare. This will help you stay calm and focused, and it will make the conversation more productive. Start by getting clear on your own financial picture. Know exactly how much debt you have, what the minimum payments are, and what your plan is (or what options you are considering). If you are unsure about the best path, you might research debt relief options. For instance, understanding the consequences of breaking a debt settlement agreement can inform your decisions and help you explain your strategy to your family. Being informed will also boost your confidence.
Next, decide who to tell and when. You do not need to announce your debt to everyone at once. Start with the person you trust most, perhaps a spouse, a parent, or a sibling. Choose a time and place that is private and free from distractions. Avoid bringing it up during a holiday gathering or when emotions are already running high. If you have a partner, you should tell them first, as your finances are likely intertwined. For children, the conversation should be age-appropriate. Young children do not need details, but they may sense tension; a simple explanation like "We are working on a money plan and need to spend less right now" can be enough. Teenagers can handle more specifics and may even appreciate being included in budgeting discussions.
Prepare what you want to say. Write down key points if that helps. You might start by expressing your love and appreciation for them, then explain that you have been facing financial difficulties and want to be honest. Share the facts without exaggerating or minimizing. It is okay to show emotion, but try to stay composed. Rehearse the conversation with a trusted friend or in front of a mirror. The more you practice, the more natural it will feel.
Consider the potential reactions. Some family members may react with shock, anger, or fear. Others may immediately offer solutions or want to lend money. Be prepared to set boundaries. If you do not want financial help, say so politely. If you do need help, be specific about what kind of support would be useful (e.g., a temporary place to live, help with childcare, or simply a listening ear). Remember that you are not obligated to accept advice or assistance that does not feel right for you.
How to Actually Have the Conversation
When the moment arrives, begin by stating your purpose. For example: "I need to talk to you about something important. I have been struggling with debt, and I want to be honest with you." Then, lay out the situation. Use clear, simple language. Avoid blaming others or making excuses. Own your part, but also acknowledge factors beyond your control, such as a job loss or medical emergency. If you have a plan in place, share it. This shows that you are taking responsibility and working toward a solution. If you are still exploring options, you can say that you are researching debt relief programs and will keep them updated.
Be open to questions. Your family may need time to process the information. They might ask how this happened, what it means for them, or how they can help. Answer honestly, but do not feel pressured to disclose every detail. You have a right to privacy, even as you are being transparent. If you feel overwhelmed, it is okay to pause and take a break. You can always continue the conversation later.
One effective approach is to frame the conversation around your commitment to change. For example, you might say: "I have made mistakes, but I am committed to fixing this. I have already looked into debt settlement and other options, and I am taking steps to reduce what I owe. I wanted you to know because I love you and I do not want to hide anything from you." This reassures your family that you are not asking them to solve your problems, but rather inviting them into your journey.
If you are married, the conversation with your spouse is especially critical. Financial infidelity (hiding debt or spending) can damage trust. Be prepared for your spouse to feel hurt or betrayed. Give them space to express their feelings, and consider seeking couples counseling if needed. Together, you can create a plan to tackle the debt as a team. If you are single, your parents or siblings may be your main support. They might worry about your future, so emphasize your proactive steps.
Common Fears and How to Overcome Them
Fear of judgment is one of the biggest barriers to opening up. You might imagine your family saying, "I told you so," or treating you differently. In reality, most families want to help. They may be sad or concerned, but they are unlikely to disown you over debt. If you have a family member who is particularly critical, you can choose not to tell them, or you can set boundaries around the conversation. Remember that your worth is not defined by your bank account.
Another fear is that your family will try to control your finances or give unsolicited advice. You can preempt this by stating what you need from them. For example: "I am not asking for money. I just need someone to talk to and maybe help me stay accountable." If they offer advice you do not want, you can politely say, "Thank you, I will consider that," and change the subject.
You might also worry about causing them stress. But keeping secrets can cause more stress in the long run. When you are honest, you give your family the opportunity to support you, and you may find that they have faced similar challenges themselves. Debt is common; millions of Americans struggle with it. You are not alone.
After the Conversation: Next Steps
Once you have told your family, the relief can be immense. But the conversation is just the beginning. Now you need to follow through on your plan. If you have not already, research reputable debt relief options. You might consider a debt settlement program, which can reduce your total debt by negotiating with creditors. Companies like Debtsend offer a free assessment to match you with partners who can help. They provide compassionate, judgment-free support and can tailor a plan to your situation. You can learn more about their services and how they connect consumers with short-term loan options at 4Payday, but remember that debt settlement is often a better fit for unsecured debt. Debtsend specializes in unsecured debt relief and can help you estimate your savings.
Keep your family in the loop as you make progress. This maintains trust and allows them to celebrate your wins with you. You might set up a monthly check-in to share updates. If you slip up, be honest about it. Nobody is perfect, and setbacks are normal. What matters is that you keep moving forward.
Finally, take care of your emotional health. Debt can be draining, and the shame associated with it can linger. Consider joining a support group or seeing a therapist who specializes in financial issues. Many people find that addressing the emotional side of debt is key to lasting recovery. Your family can be a source of strength, but professional support can provide additional tools and perspective.
When to Seek Professional Help
If your debt feels unmanageable, or if you are considering bankruptcy, it may be time to seek professional help. A certified credit counselor can review your situation and suggest options. Debt settlement companies can negotiate with creditors on your behalf. However, be cautious of scams. Legitimate companies will not ask for upfront fees before settling your debt. They will also be transparent about the risks, such as negative credit score impact and potential tax consequences. Always read the fine print and ask questions.
Debtsend is a free matching service that connects you with vetted partners. Their process is simple: you fill out a secure form, get matched with a partner, and then decide if their program is right for you. There is no obligation, and the initial consultation is free. If you are ready to take control of your debt, you can start by estimating your savings. Their goal is to help you end the stress and find your freedom.
Telling your family about debt problems is a brave and important step. It can lead to greater closeness, practical support, and a renewed sense of hope. With careful preparation and a commitment to change, you can turn this difficult conversation into the beginning of a brighter financial future.