
Long Term Budgeting Strategies After Debt Settlement
Build lasting financial stability with long term budgeting strategies after debt settlement. Call (833)-670-8023 for personalized support.
By Lila Montrose
Completing a debt settlement program can feel like reaching the summit of a steep mountain. The collection calls stop, the balances are negotiated down, and you finally have room to breathe. But what happens next determines whether that hard-won progress lasts or unravels. The months and years after settlement are where financial freedom is either secured or silently surrendered. Without a deliberate plan, old spending habits can creep back, irregular income can derail progress, and a single unexpected expense can trigger a return to the very debt you just escaped.
The good news is that you are not starting from scratch. You have already proven you can commit to a plan and see it through. Now it is time to apply that same discipline to a long term budgeting system built for your real life, not an idealized version of it. This guide walks through practical, durable strategies for managing money after debt settlement, including how to handle irregular income, use sinking funds, review your budget monthly, and catch the early warning signs of debt creep before they become a crisis.
Building a Post-Settlement Budget That Matches Real Life
Many people emerge from debt settlement with a clear number in mind: the amount they used to pay each month toward resolved accounts. But that number is now freed up, and the temptation is to treat it as new spending money. A more sustainable approach is to build a budget from the ground up based on what actually comes in and what absolutely must go out. This means separating needs from wants with brutal honesty and designing a structure that can survive a bad month, not just a good one.
Start by listing your essential expenses. These are the costs that keep a roof over your head, food on the table, and transportation running. For most households, this includes housing, utilities, groceries, basic insurance, transportation, and minimum debt payments on any remaining obligations. Once those are covered, you can allocate toward savings, irregular expenses, and discretionary spending. The goal is not to squeeze every dollar into a rigid plan, but to create a framework that prioritizes stability over short-term gratification.
If your income is irregular, perhaps from gig work, seasonal employment, or commissions, a fixed monthly budget will often fail. Instead, use a baseline budgeting method. Calculate your lowest typical monthly income over the past six to twelve months and build your essential budget around that figure. In higher-earning months, direct the surplus toward a buffer fund that covers the lean months. This approach prevents the cycle of overspending in good times and panic borrowing in slow times. You can also use a priority-based system where essential bills are paid first, then savings, then flexible spending, regardless of when the money arrives.
One practical tool is the zero-based budget, where every dollar is assigned a job at the start of the month. This does not mean you cannot have fun money, but it does mean that fun money is a deliberate line item, not an afterthought. For those who prefer more flexibility, a 50/30/20 style framework can work, where 50 percent goes to needs, 30 percent to wants, and 20 percent to savings and debt repayment. The exact percentages matter less than the habit of giving every dollar a purpose before it disappears.
Lifestyle Adjustments That Keep Spending Aligned With Income
Debt settlement often forces a temporary reduction in lifestyle, but the real challenge is maintaining those adjustments once the pressure eases. It is natural to want to celebrate by upgrading the car, moving to a nicer apartment, or resuming old shopping habits. However, lasting financial freedom usually requires keeping some of the frugality that got you through settlement and directing the difference toward savings and future goals.
Consider housing, transportation, and food, the three largest categories for most households. If you downsized during settlement, think carefully before upsizing. A lower housing payment creates breathing room that can absorb income shocks or fund emergency savings. The same applies to vehicles: keeping a reliable, paid-off car for a few extra years can free up hundreds of dollars each month. These are not permanent sacrifices; they are strategic choices that buy you time and flexibility.
Another key adjustment is learning to separate needs from wants in real time. This is not about deprivation but about intentionality. Before making a non-essential purchase, ask whether it aligns with your long term goals or whether it is a momentary impulse. A simple rule is to wait 24 hours before any purchase over a certain amount, say $50 or $100. This cooling-off period often reveals that the desire was temporary. Over time, these small decisions compound into significant savings.
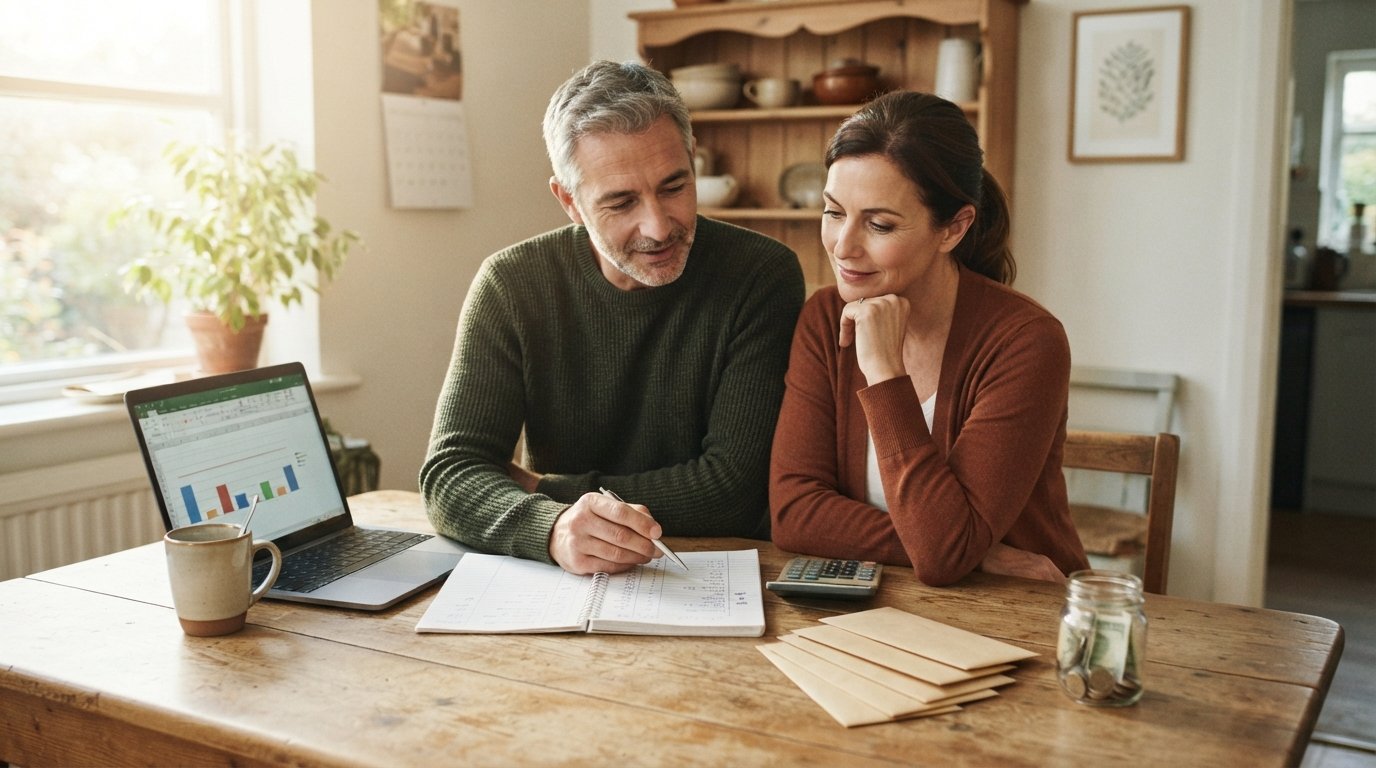
It also helps to involve your household in the budgeting process. If you have a partner or family members, shared goals reduce friction and increase accountability. Discuss what you are saving for, whether it is an emergency fund, a home repair, or a debt-free vacation, and celebrate milestones together. When everyone understands the why behind the budget, it becomes a team effort rather than a restriction imposed by one person.
Finally, beware of lifestyle inflation as your income recovers. Each raise or bonus is an opportunity to increase your savings rate rather than your spending. A good rule is to save at least half of every raise. This way, your standard of living improves gradually while your financial security grows faster than your expenses.
Using Sinking Funds for Irregular Expenses
One of the most common reasons budgets fail after debt settlement is the surprise expense. Car repairs, medical bills, holiday gifts, annual insurance premiums, and back-to-school costs are predictable in their unpredictability. If you do not plan for them, they can undo months of progress. Sinking funds solve this problem by breaking large, irregular costs into smaller, manageable monthly contributions.
A sinking fund is a dedicated savings bucket for a specific future expense. Unlike an emergency fund, which covers truly unexpected events, a sinking fund is for known expenses that do not occur every month. For example, if you expect to spend $1,200 on car maintenance and repairs over the next year, you would set aside $100 per month. When the repair bill arrives, the money is already there, and you do not have to rely on credit cards or dip into your emergency savings.
To set up sinking funds, list all the irregular expenses you can anticipate for the next 12 months. Common categories include:
- Vehicle maintenance and repairs
- Annual insurance premiums (auto, home, life)
- Holiday gifts and celebrations
- Medical and dental copays or procedures
- Home maintenance and repairs
- Travel or vacations
Once you have your list, estimate the total annual cost for each category and divide by 12 to get a monthly contribution. Then, open a separate savings account or use a budgeting app that allows you to create virtual sub-accounts. Keeping these funds separate from your everyday checking account reduces the temptation to spend them on something else.
Sinking funds are especially valuable after debt settlement because they prevent new debt from accumulating. Without them, a single car repair or holiday season can send you back to credit cards. With them, you stay in control and continue building financial stability. Over time, you can expand your sinking funds to include larger goals like a down payment on a home or a career change fund.
Monthly Budget Reviews and Adjusting for Income Changes
A budget is not a set-it-and-forget-it document. Life changes, income fluctuates, and expenses evolve. The most successful budgeters review their plan regularly, typically once a month, and make adjustments as needed. This habit keeps you connected to your money and allows you to catch problems early.
Schedule a monthly budget review at the same time each month, perhaps on the first weekend or the day after you receive your primary income. During this review, compare your actual spending to your planned spending. Identify any categories where you overspent and ask why. Was it a one-time event, or does the budget need to be adjusted to reflect reality? For example, if you consistently spend more on groceries than planned, either increase that category or find ways to reduce costs. Ignoring the mismatch will only lead to frustration.
When your income changes, whether it increases or decreases, revisit your budget immediately. A raise should trigger a review of your savings rate and debt repayment plan. A pay cut or job loss requires a temporary reallocation toward essentials and a pause on discretionary spending. You can also use a priority-based approach during lean months: cover housing, utilities, food, and transportation first, then make minimum payments on debts, then allocate whatever remains to savings and other goals.
Monthly reviews are also a good time to check your progress toward sinking fund goals and emergency savings. If you are behind, you can adjust contributions for the next month. If you are ahead, consider accelerating debt repayment or investing in your future. The key is to stay flexible and proactive rather than reactive.
For those who find monthly reviews overwhelming, start with a simple check-in: list your income, your fixed expenses, and your variable expenses, and see if the numbers balance. Even a 15-minute review can make a big difference. Over time, you can add more detail and sophistication as you become more comfortable.
Recognizing and Correcting Debt Creep Early
Debt creep is the gradual return to old borrowing habits. It often starts innocently: a small credit card balance here, a buy-now-pay-later purchase there, a personal loan to cover a shortfall. Before you know it, the minimum payments are adding up, and the stress returns. The earlier you recognize the signs, the easier it is to course-correct.
Common warning signs of debt creep include:
- Using credit cards for everyday expenses like groceries or gas because cash is tight
- Carrying a balance on a credit card from month to month
- Taking out a new loan or line of credit to cover recurring bills
- Avoiding checking your account balances because you fear what you will see
- Feeling anxious or guilty about money on a regular basis
If you notice any of these signs, take immediate action. First, pause all non-essential spending for a week or two to reset. Then, review your budget and identify where the leak is occurring. Sometimes a single category, like dining out or online shopping, is the culprit. In other cases, your income may have dropped, or your expenses may have risen, requiring a larger adjustment.
If you have already accumulated new debt, do not panic. Address it directly. If the balances are small, prioritize paying them off as quickly as possible. If they are larger, consider whether a debt management plan or a return to a structured settlement program might be appropriate. You can also reach out to a financial counselor for guidance. The important thing is to act before the situation feels overwhelming again.
Another powerful tool is automating your savings and bill payments. When money moves automatically toward savings and obligations, you are less likely to spend it on impulse. Set up transfers to your emergency fund and sinking funds on payday, and schedule automatic payments for fixed bills. This reduces the mental load and makes it harder to fall back into debt.
It is also worth understanding the consequences of breaking a debt settlement agreement, as this can have serious financial and legal repercussions. If you are ever tempted to skip a payment or walk away from an agreement, take a moment to review the consequences of breaking a debt settlement agreement to make an informed decision. Staying compliant with your settlement terms protects the progress you have made.
For those who need additional funds for emergencies or to consolidate remaining debts, exploring options like personal loans or installment loans may be helpful. You can compare offers from multiple lenders through services like FreeQuotes.Loans, which connects borrowers with personalized loan offers. However, always borrow responsibly and avoid taking on new debt unless it clearly improves your financial situation.
Strengthening Your Financial Foundation for the Long Term
Beyond the mechanics of budgeting, long term success after debt settlement depends on building a strong financial foundation. This includes growing your emergency fund, improving your credit score, and investing in your future. Each of these areas supports the others and creates a buffer against life's uncertainties.
Start by building an emergency fund that covers at least three to six months of essential expenses. If that feels daunting, begin with a smaller goal, such as $1,000, and build from there. Keep this money in a separate, easily accessible savings account. An emergency fund is your first line of defense against unexpected expenses and prevents you from turning to credit cards when things go wrong.
Next, focus on rebuilding your credit. Debt settlement can negatively impact your credit score, but with time and responsible habits, you can improve it. Make all payments on time, keep credit card balances low relative to your limits, and avoid applying for new credit too frequently. Check your credit reports regularly for errors and dispute any inaccuracies. Over time, these steps will help you qualify for better interest rates and financial products.
Finally, think about your long term goals. Do you want to buy a home, start a business, or retire comfortably? A budget is not just about managing today's expenses; it is about funding tomorrow's dreams. Allocate a portion of your income toward investments, such as a retirement account or a diversified portfolio. Even small, consistent contributions can grow significantly over time. If you are not sure where to start, consider consulting a financial advisor who can help you align your budget with your goals.
Remember, the journey after debt settlement is not about perfection. It is about progress, resilience, and making intentional choices. By building a realistic budget, adjusting to life's changes, and staying vigilant against debt creep, you can maintain your financial freedom and create a future that feels secure and hopeful.