
Options When You Cannot Afford Credit Card Minimum Payments
Facing unmanageable credit card minimums? Explore realistic options, from hardship programs to debt settlement. Call 8336708023 for personalized guidance.
By Violeta Cruz
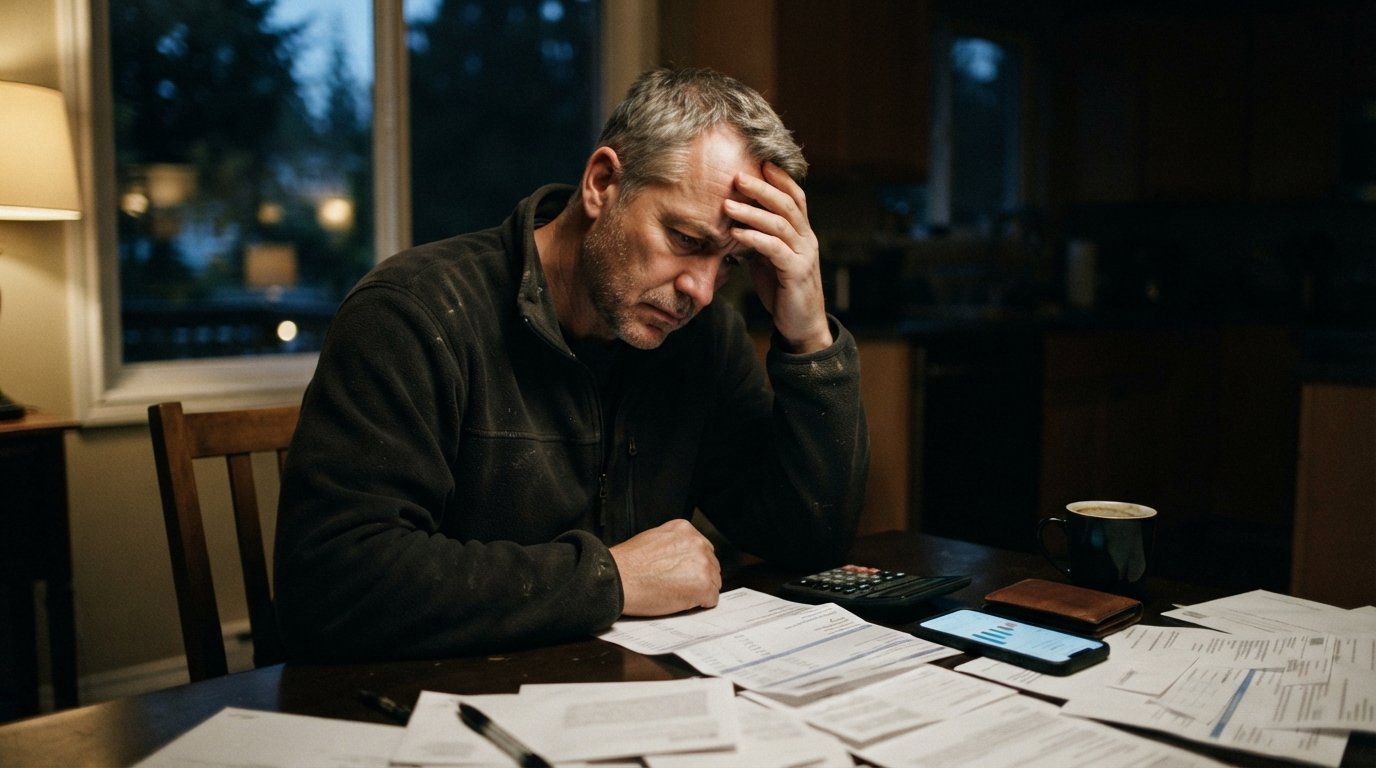
The due date is approaching, your bank account is thin, and that familiar knot tightens in your stomach. You open the statement and stare at the minimum payment line, the smallest amount you are allowed to send, and realize you cannot cover it this month. Maybe you lost hours at work, faced a medical bill, or watched every expense creep upward while your income stayed flat. Whatever brought you here, missing a credit card minimum payment feels terrifying, and the fear of late fees, penalty APRs, and phone calls from collectors can push people into paralysis.
Here is the truth that offers some relief: you have more options than you think, and none of them require you to bury your head in the sand. Creditors, counselors, and debt relief programs exist precisely because millions of Americans hit this wall every year. The key is to act quickly and choose a path that matches your situation, whether your hardship is temporary or the beginning of a longer struggle.
This guide walks through the realistic choices available when you cannot afford credit card minimum payments, from simple phone calls to structured debt settlement. Along the way, you will learn how each option affects your credit, your wallet, and your stress level, so you can make a decision with clear eyes instead of panic.
Understand What Happens If You Do Nothing
Before exploring solutions, it helps to understand the machine you are dealing with. Credit card minimum payments are calculated as a small percentage of your balance, typically one to three percent, plus any interest and fees. That design keeps you paying for years, sometimes decades, because most of your payment goes toward interest rather than the principal. If you have ever wondered why your balance barely moves despite consistent payments, our guide on what happens if you pay minimum payments forever breaks down the math and the long-term cost.
Missing a minimum payment triggers a predictable chain of consequences. First comes the late fee, usually up to $40. Then the penalty APR kicks in, which can push your interest rate above 29 percent. After 30 days, the late payment lands on your credit report, and your score can drop by 60 to 100 points or more. After 60 days, the penalty APR applies to new purchases, and after 180 days, the creditor typically charges off the account, sells it to a collection agency, and the damage deepens.
None of this means you should panic. It means you should move deliberately. The worst outcome is not a late fee. The worst outcome is ignoring the problem until your options shrink. Every step below is designed to keep you ahead of that timeline.
Contact Your Creditor Before the Due Date
The single most underused option is also the simplest: call the number on the back of your card and explain your situation. Creditors are not charities, but they are businesses that prefer to get paid something rather than nothing. Many have hardship programs, temporary forbearance, or modified payment plans for customers facing job loss, medical emergencies, or other documented setbacks.
When you call, be specific and honest. Explain what happened, how long you expect the hardship to last, and what you can realistically pay. Ask about the following possibilities:
- A reduced minimum payment for a set number of months
- A temporary interest rate reduction or suspension
- Waiver of late fees for the current cycle
- A due date change that aligns with your pay schedule
- Enrollment in a formal hardship program
Get the terms in writing before you agree to anything. Some hardship programs report to credit bureaus as "paid as agreed" or with a special comment, while others may still note the modification. Ask directly how the arrangement will appear on your credit report. Also confirm whether the program requires you to close the card, because closing an account can lower your available credit and affect your utilization ratio.
If the first representative cannot help, ask to speak with a supervisor or the hardship department. Persistence pays. A single phone call has saved many people from a cascade of fees simply because they asked before the due date instead of after.
Prioritize Payments When Money Is Tight
When you cannot cover every bill, you must decide which ones to pay first. This is not about avoiding responsibility. It is about protecting yourself from the most severe consequences while you stabilize. Secured debts like your mortgage, car payment, and utilities generally come first because losing your home or transportation makes every other problem worse.
Among unsecured debts, credit cards are often the most flexible. They do not turn off your electricity or repossess your car. That said, ignoring them entirely has costs. A workable strategy is to pay at least something toward each card, even if it is less than the minimum, and to communicate with each creditor about your situation. Partial payments do not satisfy the minimum, but they demonstrate good faith and can sometimes delay collection activity.
If you have multiple cards, consider focusing your limited funds on the one with the highest interest rate or the one closest to charging off. This is not a permanent strategy, but it buys time while you pursue one of the structured options below. The goal is to avoid a charge-off, which is far more damaging than a few late payments.
Credit Counseling and Debt Management Plans
Nonprofit credit counseling agencies offer free or low-cost sessions where a counselor reviews your income, expenses, and debts. If you enroll in a debt management plan (DMP), the agency negotiates with your creditors to lower interest rates, waive fees, and consolidate your payments into one monthly amount that you pay to the agency, which then distributes it to your creditors.
A DMP can be a good fit if your hardship is temporary and you can commit to a three-to-five-year repayment plan. It simplifies your finances and often reduces total interest. However, it does not reduce the principal balance, and it may appear on your credit report as a third-party payment arrangement. Some creditors close your accounts when you enroll, which can hurt your credit utilization. Before committing, ask the agency about fees, which are regulated in many states, and whether the plan is truly affordable for your budget.
Credit counseling is also valuable even if you do not enroll in a DMP. A counselor can help you build a budget, understand your rights, and identify which options make sense for your specific debts.
Debt Settlement: Negotiating for Less Than You Owe
When your hardship is severe and your balances are large, debt settlement may be the most realistic path. In a settlement, you or a professional negotiator offers the creditor a lump sum that is less than the full balance, and the creditor agrees to accept it as payment in full. Settlements typically range from 40 to 60 percent of the enrolled balance, though results vary based on the creditor, the age of the debt, and your ability to pay.
Debt settlement is not for everyone. It works best for people with genuine financial hardship who have already explored other options and who have or can accumulate funds to make settlement offers. It also carries real trade-offs. Creditors may not agree to settle until you are behind on payments, which means your credit score will suffer in the short term. Forgiven debt over $600 is generally reported to the IRS on a 1099-C form and may be taxable, so you should consult a tax professional. Settled accounts appear on your credit report as "settled for less than full balance," which lenders view less favorably than "paid in full."
That said, for someone facing tens of thousands of dollars in unsecured debt and no realistic way to repay it, settlement can provide a structured exit that avoids bankruptcy. A reputable debt relief matching service can connect you with partners who specialize in negotiating settlements and who provide personalized options based on your situation. These programs often involve setting aside a monthly amount into a dedicated account, which is then used to fund settlements as they are reached. Before enrolling, ask about fees, timeline, and how the program handles creditors who refuse to negotiate.
Debt Consolidation and Balance Transfers
If your credit is still in decent shape, a debt consolidation loan or a zero-percent balance transfer can simplify your payments and reduce interest. A consolidation loan combines multiple card balances into one fixed-rate loan with a predictable monthly payment. A balance transfer moves balances to a new card with a promotional zero-percent APR period, typically 12 to 21 months.
Both options have caveats. Balance transfers usually charge a three to five percent fee, and the promotional rate expires. If you do not pay off the balance before the promo ends, the regular APR applies, which can be higher than your original cards. Consolidation loans require qualifying credit and income, which may be difficult if your score has already dropped.
These tools work best when you use them to accelerate repayment, not to free up room for new spending. If you consolidate and then run up the cards again, you end up with more debt than you started with.
Borrowing Options for Urgent Gaps
Sometimes the gap is short-term: you need $500 to cover a minimum payment while you wait for a paycheck, a tax refund, or a settlement. In those cases, a small personal loan may be worth considering, though you must weigh the cost carefully. Some online platforms act as matching services that connect borrowers with third-party lenders offering short-term personal loans. One example is LendersCashLoan, a digital loan connection service that helps users submit a single request and potentially receive offers from a network of lenders. It explicitly welcomes applicants with less-than-perfect credit, which can be helpful if your score has already taken hits.
Before borrowing, compare the annual percentage rate, fees, and repayment terms. A loan that solves this month's problem but creates an unaffordable payment next month is not a solution. Also consider whether family, friends, or a local credit union might offer better terms. If you do take a loan, treat it as a bridge, not a long-term fix, and avoid using it to pay only minimums on cards that you will continue to use.
Bankruptcy as a Last Resort
Bankruptcy is not a failure. It is a legal protection designed for people whose debts have become impossible to manage. Chapter 7 liquidates non-exempt assets and discharges most unsecured debts, while Chapter 13 reorganizes debts into a three-to-five-year repayment plan. Both stop collection calls, lawsuits, and wage garnishments immediately upon filing.
Bankruptcy has significant consequences. Chapter 7 stays on your credit report for ten years, and Chapter 13 for seven. It can affect your ability to rent an apartment, buy a car, or qualify for certain jobs. It also requires court costs and, in most cases, attorney fees. For those reasons, it should be considered only after you have explored debt settlement, consolidation, and counseling. However, for someone with overwhelming debt and limited income, it can be the cleanest fresh start available.
A bankruptcy attorney can help you understand whether you qualify and what assets you would keep. Many offer free initial consultations.
Protect Yourself From Scams and Predatory Offers
Financial hardship attracts predators. Be skeptical of any company that demands upfront fees before settling a debt, promises to remove accurate negative information from your credit report, or guarantees a specific settlement amount. Legitimate debt relief companies typically charge fees only after they successfully settle a debt or after you make a payment toward a settlement. They also disclose that results vary and that settlement can harm your credit.
Never give bank account or Social Security information to a company you have not verified. Check with your state attorney general and the Consumer Financial Protection Bureau. If an offer sounds too good to be true, it almost certainly is.
Build a Plan and Take the First Step
You do not have to solve everything today. You only have to take one step. Start by listing every debt, its balance, minimum payment, interest rate, and due date. Then calculate your true monthly surplus, the amount left after essential expenses. That number tells you which options are realistic.
If you have a small surplus and temporary hardship, call your creditors and ask for a hardship plan. If you have multiple cards and decent credit, explore consolidation or a DMP. If your balances are large and your hardship is severe, debt settlement deserves serious consideration. A free debt assessment can help you estimate savings and compare personalized options without affecting your credit score.
The most important thing is to act before the situation worsens. Every day you wait, fees accumulate and options narrow. You are not alone, and you are not without choices. With clear information and a willingness to ask for help, you can move from fear to a plan.