
Secured vs Unsecured Debt and Debt Relief Options
Understand secured vs unsecured debt and debt relief options. Call (833)-670-8023 for a free assessment and personalized guidance.
By Aria Caldwell
Your car loan and your credit card balance are both debts, but they behave very differently when money gets tight. One can take your car. The other usually cannot. Understanding the difference between secured and unsecured debt is the first step toward choosing a debt relief option that actually works for your situation. This article breaks down both categories, explains which debts can be settled or consolidated, and shows how to get personalized guidance without guessing.
What Makes a Debt Secured or Unsecured
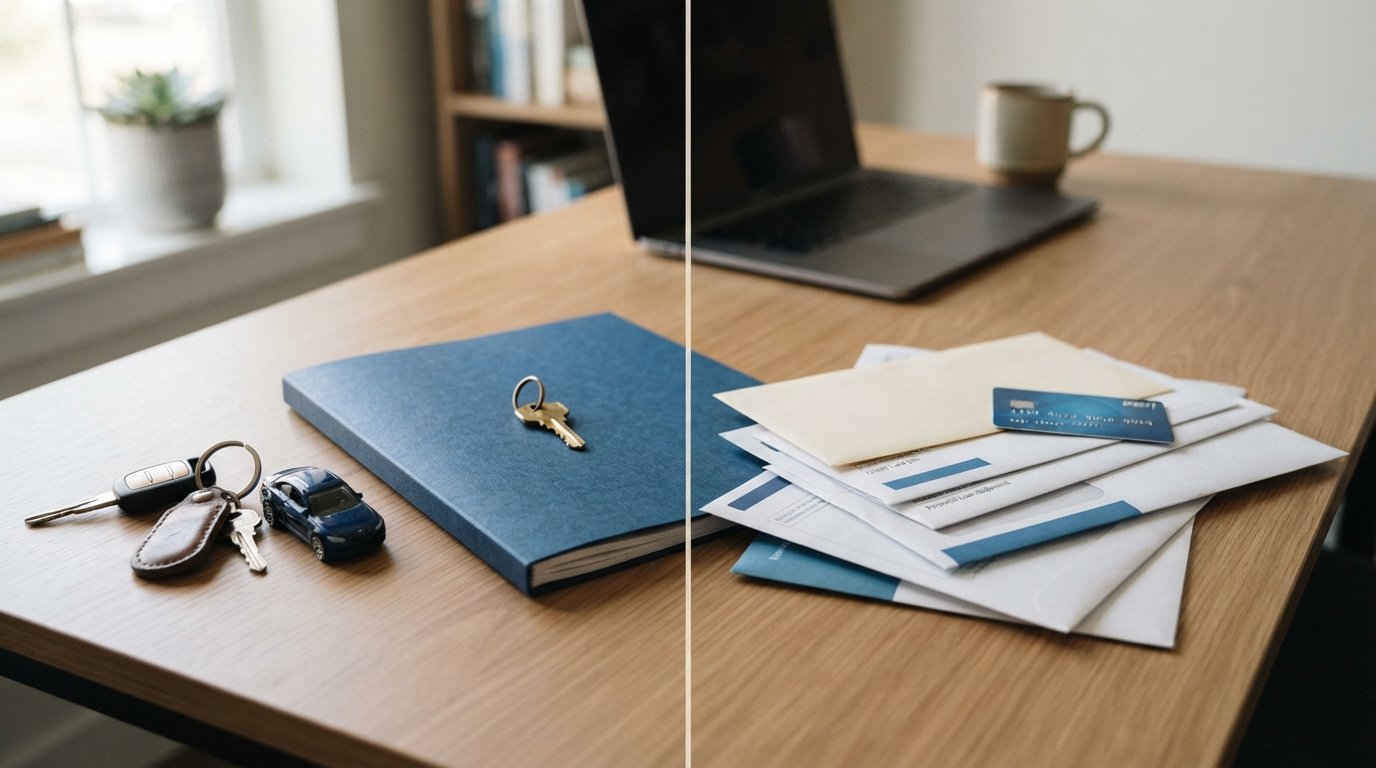
The dividing line is simple: collateral. A secured debt is tied to an asset, and the lender can seize that asset if you stop paying. An unsecured debt has no asset backing it. The lender relies on your promise to pay and your creditworthiness, not on the ability to repossess something specific.
Secured debts typically include:
- Auto loans (the vehicle is collateral)
- Mortgages and home equity loans (the home is collateral)
- Secured credit cards (a cash deposit serves as collateral)
- Personal loans backed by savings or other assets
Unsecured debts typically include:
- Credit card balances
- Personal loans without collateral
- Medical bills
- Payday loans and collection accounts
- Student loans (federal and most private)
The practical difference shows up fast when you miss payments. With a secured debt, the lender can repossess the car or foreclose on the home. With an unsecured debt, the lender cannot simply take your furniture. Instead, they may sue you, obtain a judgment, and then pursue wage garnishment or a bank levy, but that process takes time and varies by state. This is why unsecured debts are the primary target of most debt relief programs: there is no collateral to reclaim, so negotiation becomes the main tool.
Why Unsecured Debts Are Commonly Settled
Debt settlement works by negotiating with creditors to accept less than the full balance owed. Creditors agree to this because something is better than nothing, especially when they believe you may file for bankruptcy or simply never pay. Unsecured debts are ideal candidates because they have no collateral to fall back on. If you stop paying a credit card, the issuer cannot repossess your groceries or your sofa. Their only leverage is collection activity, credit reporting, and potential lawsuits.
Credit cards, personal loans, medical bills, and collection accounts make up the bulk of debt settlement programs. These balances are often unmanageable because of high interest rates and compounding fees. A single medical emergency or a stretch of unemployment can turn a manageable credit card balance into an overwhelming monthly obligation. When that happens, settling for a reduced lump sum or a structured payout can provide real relief.
It is important to note that debt settlement is not right for everyone. It typically suits people facing genuine financial hardship who have already explored other options and who have a meaningful amount of unsecured debt. If you can manage your payments with a budget adjustment or a lower-interest consolidation loan, those may be better first steps. For those who cannot, settlement can offer a path forward.
If you want to explore how settlement works in practice, our guide on top debt relief options in Tampa Florida for 2026 walks through the process step by step.
How Secured Debts Are Treated Differently
Secured debts are rarely included in debt settlement programs. The reason is straightforward: the lender already has collateral. If you stop paying your auto loan, the lender repossesses the car. If you stop paying your mortgage, the lender forecloses. There is no incentive for the lender to negotiate a reduced payoff because they can recover value through the asset.
That said, secured debts are not completely outside the realm of relief. Options for secured debts include:
- Loan modification (for mortgages)
- Refinancing (for auto loans or mortgages)
- Chapter 13 bankruptcy (which can restructure secured debt while protecting the asset)
- Reaffirmation agreements in bankruptcy (keeping the asset and continuing payments)
These options are different from settlement because they focus on making payments more affordable rather than reducing the total balance. For example, extending the term of an auto loan lowers your monthly payment but may increase the total interest you pay. A mortgage modification might reduce your interest rate or extend your repayment period. These are still forms of debt relief, but they operate on different rules.
Understanding this distinction matters because many people assume all debts can be settled. They cannot. If you have a mix of secured and unsecured debt, a debt relief program will typically focus on the unsecured portion while you continue paying secured debts to protect your home or car.
Which Debts a Debt Relief Program Can Include
Most debt relief programs, including debt settlement and debt management plans, focus on unsecured debts. The following debts are commonly eligible:
- Credit card balances (including store cards)
- Personal loans (unsecured)
- Medical bills
- Payday loans
- Collection accounts
- Some private student loans (less common)
Debts that are typically not included:
- Mortgages
- Auto loans
- Federal student loans
- Tax debt
- Child support and alimony
- Fines and penalties
The reason federal student loans and tax debt are excluded is that the government has extraordinary collection powers, including wage garnishment and tax refund offsets, and they rarely negotiate settlements outside of specific programs. Child support and alimony are court-ordered and not dischargeable in bankruptcy, so they are not candidates for settlement either.
If you are struggling with a mix of debts, a debt relief program can still help by addressing the unsecured portion while you work with your secured lenders separately. The goal is to reduce the total burden, not to eliminate every obligation.
For those facing urgent financial needs, including debt consolidation, a digital loan connection service like LendersCashLoan can help you explore potential short-term personal loan offers from a network of third-party lenders. This can be a useful option if you prefer to consolidate unsecured debts into a single payment rather than negotiate settlements.
Debt Relief Options for Unsecured Debt
When unsecured debt becomes unmanageable, several relief options are available. Each has trade-offs, and the best choice depends on your income, credit score, and how much debt you have.
Here are the most common options:
- Debt settlement: Negotiate with creditors to pay less than the full balance. This can reduce your total debt but may damage your credit score and have tax implications on forgiven debt.
- Debt consolidation: Combine multiple debts into a single loan with one monthly payment. This can simplify payments and lower interest rates if you qualify for a good loan.
- Debt management plan: A credit counseling agency negotiates lower interest rates and a single payment. You repay the full balance but with more affordable terms.
- Credit counseling: A counselor helps you create a budget and a plan to repay debt. This is often a first step before more aggressive options.
- Bankruptcy: A legal process that can discharge unsecured debts. Chapter 7 liquidates assets, while Chapter 13 restructures debt. This is typically a last resort.
Each option has different effects on your credit score, timeline, and total cost. Debt settlement typically has the largest negative impact on credit but can reduce your total debt the most. Debt management plans have a smaller credit impact but require you to repay the full balance. Bankruptcy has the most severe credit impact but provides the most comprehensive relief.
If you are considering debt settlement, it is important to work with a reputable company that explains the risks and helps you understand the tax consequences. Forgiven debt over $600 is generally considered taxable income by the IRS, so you may owe taxes on the amount saved. A good program will disclose this upfront.
How to Get Personalized Guidance Through a Free Assessment
Every financial situation is different. A debt relief option that works for your neighbor may not work for you. That is why a personalized assessment is the best starting point. It helps you understand which debts are eligible, what relief might look like, and what the trade-offs are.
At Debtsend, the process is designed to be simple and stress-free. You start with a free, no-obligation debt assessment. This can be done online in under five minutes or over the phone. The assessment does not affect your credit score. Based on your information, you are matched with third-party partners who may offer a customized strategy, which could include debt settlement, consolidation-style plans, or other options.
Here is what to expect:
- Free evaluation: Share basic information about your debts, income, and financial hardship. No credit impact.
- Matching: You are connected with partners who specialize in your type of debt and situation.
- Custom plan: Partners may design a plan that includes one monthly payment, reduced rates, and a path to resolve your debt.
The goal is to end the stress and find your freedom. You do not have to navigate this alone. Compassionate, judgment-free support is available, and the initial consultation is completely free. If you are ready to see what options might be available to you, start with an estimate of your potential savings.
Debt relief is not a one-size-fits-all solution. Whether you choose settlement, consolidation, or another path, understanding the difference between secured and unsecured debt is the foundation. With the right information and a personalized assessment, you can make a decision that moves you toward financial stability.