
Sued for Unpaid Medical Bills? What Happens Next
A medical debt lawsuit can lead to garnishment, but responding on time and negotiating can reduce what you owe. Know your options and protect your finances.
By Matteo Alvarez
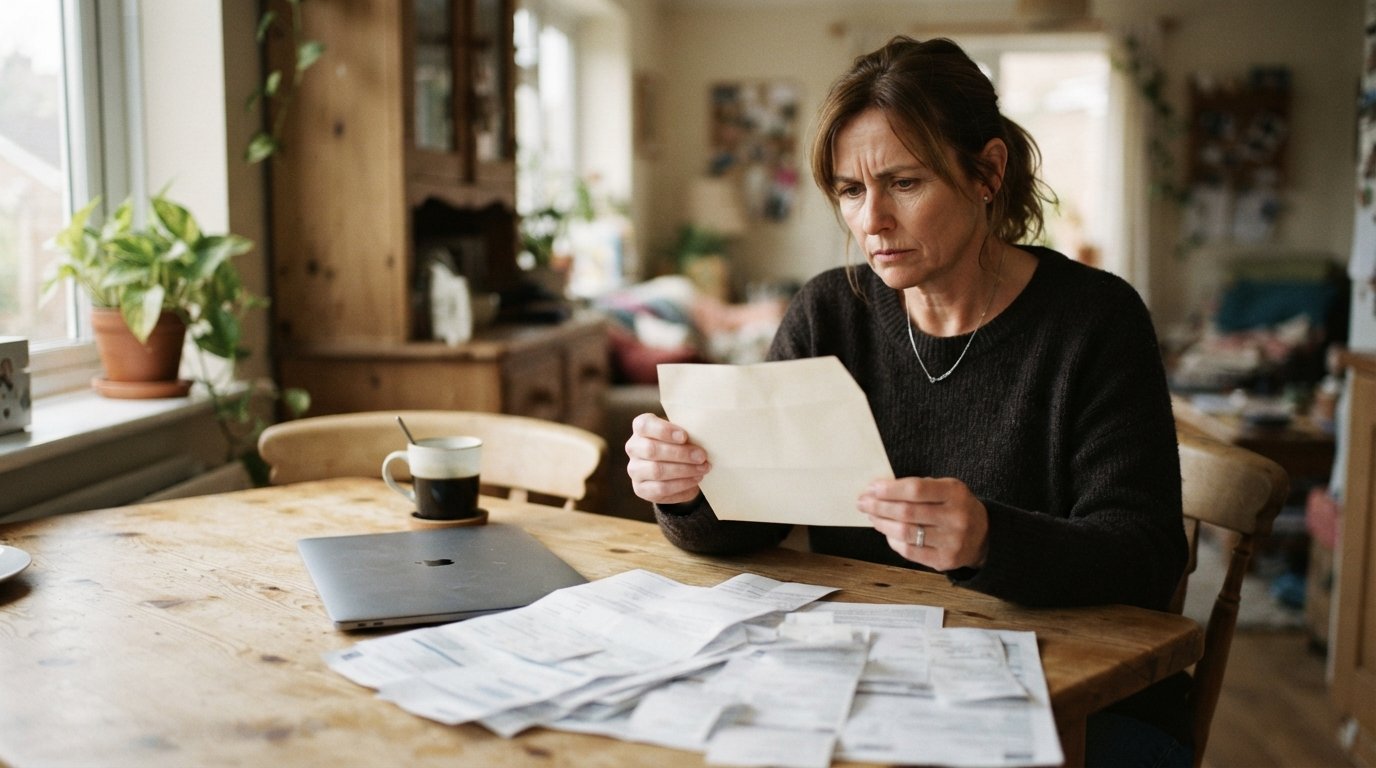
The envelope looks official, and the words jump off the page: you are being sued. If you are facing a lawsuit over unpaid medical bills, you are not alone. Medical debt is one of the most common reasons people end up in civil court, and the experience can feel isolating and frightening. But a lawsuit is not the end of your story. Understanding what happens if you get sued for unpaid medical bills, from the initial complaint to the final judgment and beyond, gives you the power to respond strategically instead of panicking. This guide walks you through each stage of the process, explains your rights, and shows you how to protect yourself while working toward a real financial recovery.
Why Medical Providers Sue and What It Means for You
Hospitals, physician groups, and ambulance companies typically sue only after months of nonpayment and failed collection attempts. Unlike credit card issuers, many healthcare providers have in-house collection teams or sell accounts to debt buyers who are aggressive about recovery. When a provider files suit, it is usually because the bill is large enough to justify court costs and the statute of limitations has not yet expired. The lawsuit itself is a formal demand: the provider claims you owe a specific amount and asks a court to enforce that debt.
The good news is that medical debt lawsuits follow a predictable pattern. Once you understand the steps, you can make informed decisions at each stage. You may have defenses, you may be able to negotiate a settlement, or you may qualify for financial assistance programs that reduce or eliminate the balance. Ignoring the lawsuit is the one response that almost always makes things worse.
It also helps to know that medical bills are unsecured debt, which means they are not tied to any collateral like a car or home. If you are dealing with several types of unsecured debt at once, including credit cards and personal loans, a structured program may help you resolve them together. In our guide on medical bills in debt settlement, we explain how negotiation works and what to expect from the process.
The Lawsuit Timeline: From Complaint to Judgment
Every state has its own rules, but the general sequence of a medical debt lawsuit is consistent across the country. The clock starts when the provider or debt collector files a complaint with the court and arranges for you to be served. Service usually happens in person, by mail, or sometimes by publication if you cannot be located. The moment you receive the complaint, the clock starts ticking on your deadline to respond.
If you do nothing, the court will likely enter a default judgment against you. That judgment gives the creditor powerful tools to collect, including wage garnishment, bank account levies, and property liens. A default judgment can haunt you for years, so responding on time is critical. Here is a simplified timeline of what typically happens:
- Complaint and summons: You receive legal papers stating the amount owed and the deadline to respond, often 20 to 30 days.
- Your answer: You file a written response admitting or denying the allegations and raising any defenses.
- Discovery: Both sides exchange information and evidence, such as billing records and proof of the debt.
- Settlement or trial: The case may resolve through negotiation or proceed to a hearing where a judge decides.
- Judgment and collection: If the creditor wins, they can seek garnishment or liens to collect the debt.
Each step offers an opportunity to change the outcome. Even after a judgment, you may be able to negotiate a payment plan or settle for less than the full amount. The key is to stay engaged and avoid letting the case slip into default.
Your Rights and Defenses When Facing a Medical Debt Lawsuit
Consumers have more protections than they often realize. The Fair Debt Collection Practices Act (FDCPA) limits how collectors can contact you and prohibits abusive or deceptive tactics. If a debt buyer sues you, they must prove they own the debt and that the amount is accurate. Many lawsuits are filed with incomplete documentation, and raising that issue can lead to a dismissal or a more favorable settlement.
Common defenses in medical debt cases include:
- Incorrect amount: The bill may include charges that were already paid by insurance or that violate billing rules.
- Lack of proof: The plaintiff cannot produce a signed agreement or a clear chain of ownership.
- Statute of limitations: The time allowed to sue has expired, which varies by state and type of debt.
- Identity theft or mistaken identity: The debt may not belong to you at all.
- Insurance errors: The provider may have failed to bill your insurer correctly, leaving you with a balance that should not exist.
You do not need to be a lawyer to assert these defenses, but you do need to respond in writing. Many courts have self-help centers or online forms for consumers. If the amount is large or the case is complex, consulting a consumer attorney, even for a single session, can be worthwhile. Some legal aid organizations offer free help to low-income defendants.
What Happens If You Lose: Garnishment, Liens, and Bank Levies
If the court enters a judgment against you, the creditor can use legal collection tools. Wage garnishment allows them to take a portion of your paycheck, though federal law caps the amount and many states set lower limits. Bank levies freeze and withdraw funds from your account, sometimes leaving you unable to pay rent or buy groceries. Property liens attach to real estate and must be resolved before you can sell or refinance.
The impact goes beyond your bank account. A judgment appears on your credit report and can remain there for years, making it harder to qualify for loans, apartments, or even some jobs. The stress of constant collection pressure can affect your health and relationships. This is why addressing the lawsuit early, before a judgment is entered, is so important.
If you are already facing garnishment or levies, you may still have options. Some states allow you to claim exemptions for certain amounts, and you can negotiate to lift the garnishment in exchange for a payment plan. Bankruptcy can also stop collection, but it is a serious step with long-term consequences. Many people find that a negotiated settlement or a structured debt relief program is a better fit.
Negotiating a Settlement Before or After Judgment
Settlement is often the most practical outcome for both sides. The creditor wants to recover money without the time and expense of trial, and you want to resolve the debt without a judgment hanging over you. Negotiations can happen at any stage, from the first collection call to post-judgment collection. The key is to communicate clearly and get any agreement in writing before you make a payment.
When negotiating, consider what you can realistically afford. A lump sum may secure a larger reduction, while a payment plan spreads the cost over time. Be wary of agreeing to amounts you cannot sustain; a defaulted settlement can leave you worse off. If you are working with a debt settlement company, they can handle negotiations on your behalf and help you build a savings plan. For urgent medical expenses, some people also explore personal loan options through FreeQuotes.Loans to consolidate bills, though it is important to compare offers carefully and avoid taking on high-interest debt without a repayment plan.
If you have multiple medical bills in collections, a comprehensive approach may work better than settling one at a time. Debt settlement programs often negotiate with several creditors simultaneously, aiming to reduce the total balance and simplify your payments. Just be aware that settlement can affect your credit score and may have tax implications if forgiven debt exceeds certain limits. Consulting a tax professional is wise before finalizing any agreement.
How to Respond Step by Step
If you have been served with a lawsuit, the worst thing you can do is nothing. Here is a practical sequence to follow:
- Read the complaint carefully. Note the plaintiff, the amount, and the response deadline.
- Gather your records. Collect bills, insurance statements, and any correspondence with the provider or collector.
- File a written answer with the court. Deny the allegations you dispute and list your defenses.
- Consider negotiation or legal help. Contact the plaintiff's attorney to discuss settlement, or consult a consumer lawyer.
- Show up to all hearings. Missing a court date can result in a default judgment against you.
Following these steps shows the court and the creditor that you are engaged and serious. It also preserves your ability to negotiate from a position of strength rather than desperation.
Protecting Your Finances and Moving Forward
Once the lawsuit is resolved, your focus should shift to rebuilding. If you settled for less than the full amount, check your credit report to ensure the account is reported accurately. Dispute any errors and keep documentation of your settlement agreement for at least seven years. Rebuilding your credit takes time, but on-time payments, low balances, and a mix of credit types can help.
It is also worth reviewing how you handle medical bills in the future. Ask for itemized statements, verify insurance coverage, and apply for hospital financial assistance programs before bills go to collections. Many providers offer discounts for prompt payment or income-based reductions. If you are uninsured, ask about self-pay rates, which are often lower than billed charges.
Finally, remember that you are not defined by a lawsuit or a medical bill. Taking action, even a small step like filing an answer or calling a debt relief service, puts you back in control. With the right information and support, you can resolve the debt and move toward a more stable financial future.