What to Do When You Owe More Than Your Income
Owe more than you earn? Learn what to do when you owe more than your income, from assessing your debts to choosing relief options that reduce stress.
By Calvin Brooks
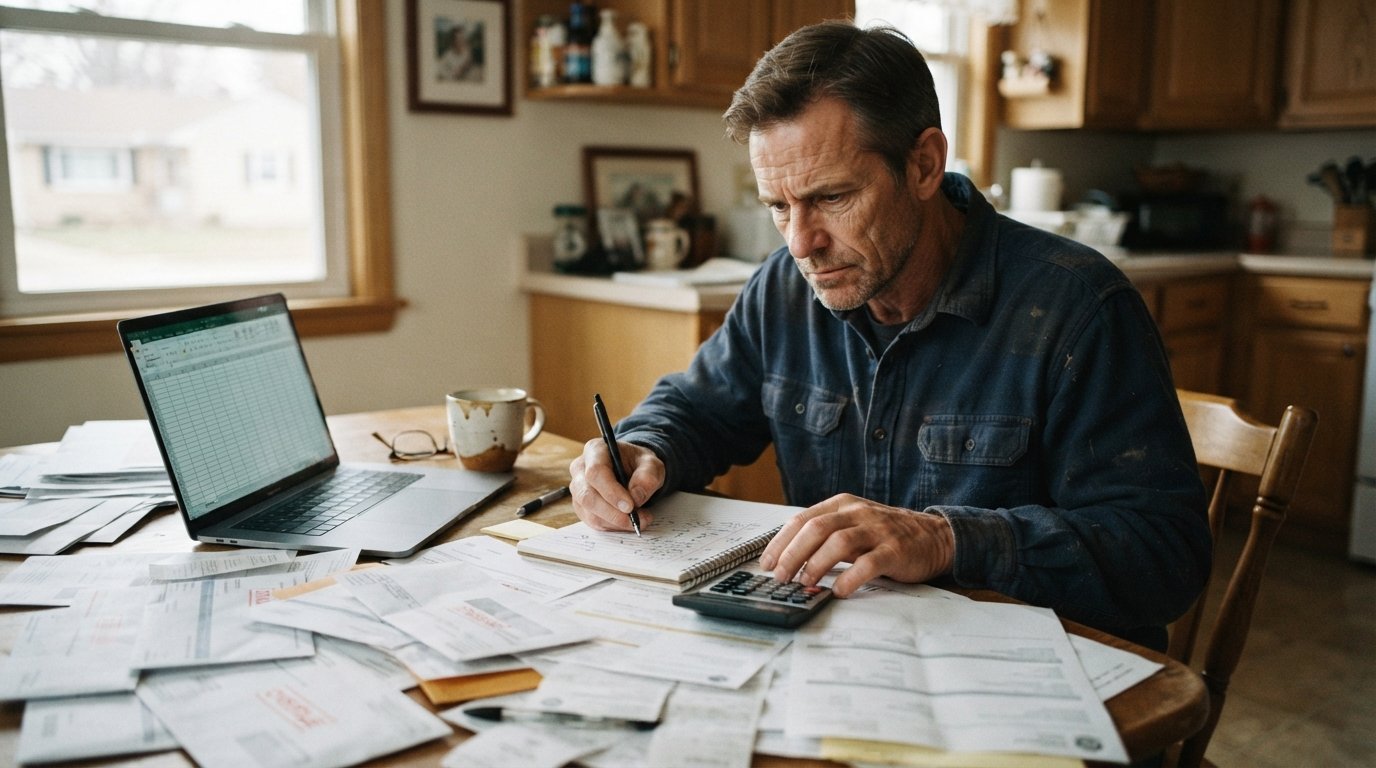
The moment you realize your total debt payments exceed what you bring home each month is a moment of genuine fear. Maybe you have been juggling credit cards, personal loans, and medical bills for months, and the math simply stopped working. You are not alone, and more importantly, you are not out of options. When you owe more than your income, the worst thing you can do is freeze. The best thing you can do is act with a clear plan.
This guide walks you through the practical, step-by-step decisions that can move you from panic to progress. It covers how to assess your real numbers, which debt relief paths exist, how to protect yourself from collectors, and how to rebuild once the pressure eases. Throughout, the focus stays on realistic actions you can take this week, not vague encouragement.
Face the Numbers Before You Make Any Moves
Before you call anyone or sign anything, you need a complete picture of what you owe and what you earn. Denial is the most expensive habit in personal finance. Sit down with every statement, log into every account, and write down the balance, interest rate, minimum payment, and due date for each debt. Include credit cards, personal loans, medical bills, payday loans, collection accounts, and anything else that demands money each month.
Next, calculate your true monthly income after taxes and essential expenses. Subtract rent or mortgage, utilities, groceries, transportation, insurance, and childcare. What remains is what you can realistically put toward debt. In many cases, that number is far smaller than the total minimum payments, which is exactly why the situation feels impossible.
A simple framework can help you see where you stand:
- Total unsecured debt: Add up all balances that are not tied to a house or car.
- Total minimum payments: Add every required monthly payment.
- Monthly surplus or shortfall: Subtract minimums from your income after essentials.
- Debt-to-income ratio: Divide monthly debt payments by gross monthly income.
If your debt-to-income ratio is above 40 percent, you are in territory where many lenders and relief programs consider you a candidate for hardship options. A related resource on our site explains practical ways to lower your debt to income ratio fast, which can improve your standing with creditors and open doors to better solutions.
Once you have the numbers, resist the urge to blame yourself. Medical emergencies, job loss, divorce, and rising costs push millions of Americans into this exact position every year. The goal now is not to relitigate the past. It is to build a realistic path forward using the resources you actually have.
Prioritize Essentials and Protect Your Household
When money is tight, every dollar feels contested. You need a clear hierarchy. Housing, food, utilities, transportation to work, and necessary medical care come first. Credit card payments, while important, cannot take precedence over keeping a roof over your head or keeping the lights on. Creditors can pressure you, but they cannot force you to choose their payment over your family's basic needs.
Contact your utility companies and explain your situation. Many offer hardship programs, payment arrangements, or budget billing that spreads costs more evenly. The same is true for some landlords and mortgage servicers, though those conversations require care and documentation. If you have a car loan, call the lender before you miss a payment, not after. Lenders are far more willing to work with someone who communicates early.
For unsecured debts like credit cards and medical bills, you have more flexibility than you might think. Federal and state laws limit what collectors can do, and many creditors have internal hardship departments. The key is to call, explain your circumstances honestly, and ask specifically what programs exist for someone in your situation. Write down the name of every representative you speak with and the date of the call.
Understand Your Debt Relief Options
When your debt load exceeds your income, you generally have five broad paths: do nothing and hope, try to manage it yourself, consolidate, enter a debt management plan, negotiate a settlement, or file bankruptcy. Each has trade-offs. The right choice depends on how much you owe, how much you can realistically pay, and how much damage your credit can absorb.
Debt consolidation combines multiple debts into one loan, ideally at a lower interest rate. This can simplify your payments and reduce stress, but it does not reduce what you owe. If your credit is already damaged, you may not qualify for a rate that actually helps. It works best for people with stable income and moderate debt who can commit to not running up the cards again.
Debt management plans, often offered through credit counseling agencies, negotiate lower interest rates and one monthly payment. These plans can take four to five years and typically require you to close your credit cards. They are a good fit for people who can afford a meaningful monthly payment but need structure and lower rates.
Debt settlement is different. Instead of paying everything back with interest, a settlement company negotiates with creditors to accept less than the full balance. This can dramatically reduce what you owe, but it comes with real consequences: your credit score will likely drop, accounts may go delinquent during the process, and forgiven debt may be taxable. Settlement is generally best for people with genuine hardship and substantial unsecured debt who cannot realistically repay the full amount.
Bankruptcy is the legal reset button. Chapter 7 can wipe out most unsecured debt, while Chapter 13 creates a repayment plan. Bankruptcy carries long-lasting credit impact and should be considered carefully, but for some people it is the most honest and effective solution. A qualified bankruptcy attorney can help you understand whether it fits your situation.
If you are exploring loan-based options to buy time or consolidate, a service like FreeQuotes.Loans can connect you with lenders who offer personalized offers, including options for less-than-perfect credit. That said, borrowing your way out of debt only works if the new loan genuinely lowers your total cost and you commit to changing the behavior that created the debt.
How Debt Settlement Works in Practice
Debt settlement is one of the most misunderstood options, so it deserves a closer look. The basic idea is straightforward: a company negotiates with your creditors to accept a lump sum that is less than what you owe. You typically stop paying your creditors directly and instead make monthly deposits into a dedicated account. As funds accumulate, the settlement company uses them to negotiate and pay settlements one by one.
This process is not quick. Most programs take two to four years. During that time, your accounts may become delinquent, you may receive collection calls, and your credit score will likely suffer. The trade-off is that you may resolve your debt for significantly less than the full balance, sometimes 50 to 60 percent before fees. That can be life-changing for someone facing decades of minimum payments.
Not everyone qualifies. Most reputable settlement companies look for a genuine financial hardship, such as job loss, medical crisis, or divorce, and a minimum amount of unsecured debt, often around $7,500 to $10,000. Secured debts like mortgages and car loans are not part of the program because the lender can repossess the asset. Federal student loans are also generally excluded.
Before enrolling, ask detailed questions about fees, timelines, and what happens if a creditor refuses to settle. A legitimate company will be transparent about the risks, including credit score damage and potential tax liability on forgiven debt. If a company promises specific results, guarantees that your credit will not be affected, or asks for large upfront fees before settling any debt, treat that as a warning sign.
Communicating With Creditors and Collectors
Once you decide on a path, communication becomes your most important tool. Creditors and collectors are not monoliths. They have policies, supervisors, and incentives. Knowing how to talk to them can mean the difference between a manageable arrangement and a lawsuit.
Start by requesting written verification of every debt. Under the Fair Debt Collection Practices Act, you have the right to ask a collector to validate the debt. If they cannot prove you owe it, they must stop collection efforts. This step also buys you time and creates a paper trail. Send requests in writing and keep copies of everything.
If you are working with a settlement company, they will handle negotiations on your behalf. If you are negotiating yourself, be polite but firm. Explain your hardship, state what you can afford, and ask what they are willing to accept. Many creditors have settlement departments that routinely accept less than the full balance, especially on older accounts. Get any agreement in writing before you send a payment, and never give a collector direct access to your bank account.
If you are sued, do not ignore it. A default judgment can lead to wage garnishment or bank levies. Respond to the lawsuit, show up to court, and consider consulting a consumer law attorney. Many offer free or low-cost consultations, and some work on a contingency basis.
Rebuilding After the Storm
Once your debt is resolved or your plan is underway, the work shifts from survival to rebuilding. This phase matters just as much as the crisis phase, because the habits you build now determine whether you end up back in the same position. Start by creating a budget that reflects your actual income and expenses, not an idealized version of them. Give every dollar a job, and build in a small buffer for the unexpected.
Rebuilding credit takes time, but it is very doable. Consider a secured credit card, which requires a cash deposit and reports to the credit bureaus. Use it for small, recurring purchases and pay the balance in full each month. Keep your credit utilization below 30 percent, and ideally below 10 percent. Over time, on-time payments and low balances will gradually improve your score.
Also focus on building an emergency fund. Even a few hundred dollars can prevent a future crisis from turning into new debt. Automate a small transfer to savings each payday, and treat it as a non-negotiable bill. The goal is not to be perfect. The goal is to build resilience so that the next surprise does not undo your progress.
When to Get Professional Help
There is no shame in asking for help, and in many cases, professional guidance saves money and time. If your debt feels unmanageable, if you are receiving collection calls or lawsuits, or if you cannot see a realistic path to repayment, it is time to talk to someone. Options include nonprofit credit counselors, consumer law attorneys, and reputable debt relief companies.
A good starting point is a free, no-obligation debt assessment. These evaluations help you understand your options and often connect you with programs you did not know existed. They also give you a chance to ask questions in a judgment-free setting. The key is to choose a provider that is transparent about fees and risks, and that does not pressure you into a decision.
If you are considering debt settlement, look for a company that explains both the benefits and the downsides clearly. Ask how they handle creditor lawsuits, what happens if you want to cancel, and how fees are structured. A trustworthy partner will welcome those questions.
Owing more than your income is a serious problem, but it is not a permanent one. The path forward starts with honesty about your numbers, a clear-eyed look at your options, and a willingness to take the first step. Whether that step is a phone call, a written budget, or a consultation with a debt relief professional, it moves you out of paralysis and into action. That is where real change begins.