
What to Expect at the Start of a Debt Settlement Program
See what happens in the first weeks of a debt settlement program, from onboarding to your first savings deposit, and how to start strong.
By Lila Montrose
Enrolling in a debt settlement program is a decisive step toward regaining control of your financial life, but the first few weeks can feel unfamiliar and even a little unsettling. You are moving from a cycle of minimum payments and mounting interest into a structured negotiation process that is designed to reduce what you owe. Knowing exactly what happens after you sign up removes much of the guesswork and helps you stay committed when the process tests your patience. This guide walks you through the early stages step by step, from the initial consultation to your first dedicated savings deposit, so you can approach the program with realistic expectations and confidence.
Your First Week: Enrollment, Onboarding, and the Initial Consultation
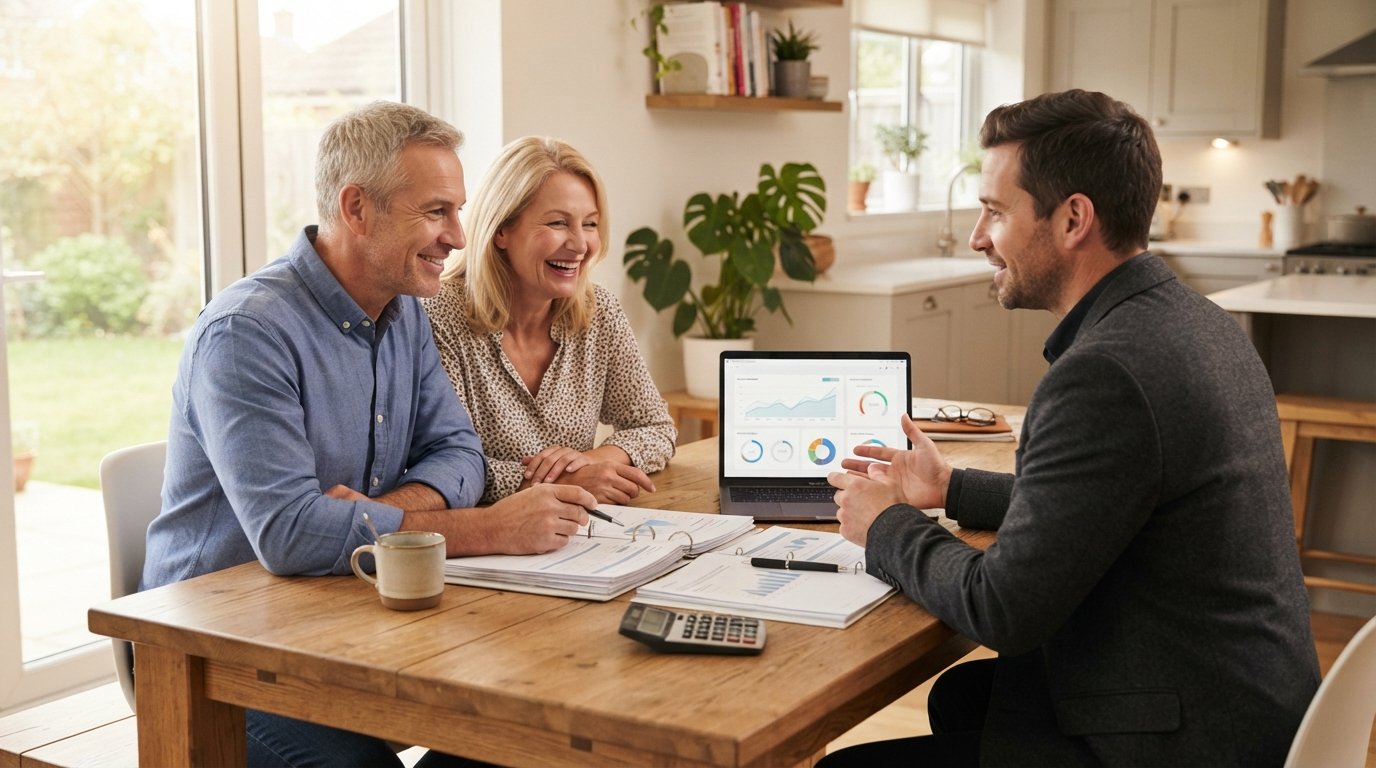
The journey typically begins with a free, no-obligation debt assessment. During this phase, you share details about your unsecured debts, including credit card balances, personal loans, medical bills, and collection accounts. A debt specialist reviews your income, monthly expenses, and the total amount you owe to determine whether debt settlement is a viable fit. This conversation is not a commitment; it is an evaluation designed to match you with options that align with your hardship. If you are exploring alternatives to bankruptcy, this initial review is where you and your specialist map out a potential path forward.
Once you decide to enroll, you will complete a formal agreement and set up your dedicated settlement account. This account is not a payment to your creditors; it is a savings vehicle where you accumulate funds that will later be used to negotiate lump-sum settlements. Many people find this structure confusing at first, so here is a quick breakdown of what happens during onboarding:
- Documentation review: You provide statements, creditor information, and proof of hardship so the team can verify your enrolled debts.
- Account setup: A third-party FDIC-insured account is opened in your name, and you receive instructions for making monthly deposits.
- Welcome packet: You receive a schedule, program terms, and contact information for your dedicated account representative.
- Initial deposit: Your first monthly savings deposit is scheduled, often aligned with your pay cycle.
It is important to understand that your creditors are not immediately contacted during this first week. The program needs time to build a sufficient reserve before negotiations begin. This waiting period is deliberate: creditors are more likely to accept a settlement when they see a credible lump sum ready to be disbursed. Use this time to ask questions, confirm your deposit schedule, and familiarize yourself with the program portal or app.
If you are considering how this early phase might affect future financial goals, you may wonder whether homeownership is still possible. In our guide on buying a house after debt settlement, we explain how lenders view settled accounts and what steps can strengthen your mortgage application down the road. The key takeaway is that the early program stages are foundational, and the habits you build now will influence your long-term credit recovery.
How Your Dedicated Account Works and Why It Matters
One of the most common surprises at the start of a debt settlement program is the realization that you stop paying your creditors directly. Instead, your monthly deposit goes into a dedicated account that you control. This shift can feel counterintuitive, especially if you have spent years prioritizing on-time payments. However, the logic is straightforward: creditors negotiate more readily when they see that you have accumulated a meaningful portion of the debt in cash. A lump-sum offer of 40 to 60 percent of the balance is far more persuasive than a promise to pay small amounts over many years.
Your dedicated account is typically managed by a third-party financial institution, and you retain ownership of the funds. The program does not take fees from your deposits before settlements are reached; most reputable programs charge fees only after a debt is successfully settled. This structure aligns incentives: the company earns its fee when you save money, not before. You should receive a clear schedule showing how much you need to deposit each month and how long it will take to build a settlement reserve for each enrolled debt.
During this phase, you will also learn how to monitor your account balance and track progress. Many programs provide online dashboards that show how much has been saved toward each creditor. Watching that number grow can be motivating, especially in the first few months when no negotiations have yet occurred. If you are facing urgent financial needs alongside your debt, such as an unexpected car repair or medical bill, you might explore short-term loan options through services like LendersCashLoan to bridge the gap without derailing your settlement savings. Just be cautious about taking on new debt while enrolled, as it can complicate your program and your overall financial picture.
Communication with Creditors: What Happens and When
In the early weeks, you may still receive collection calls and letters. This can be alarming, but it is a normal part of the process. Your program typically sends a limited power of attorney or authorization letter to your creditors, instructing them to direct communication to your account representative. However, it can take time for that instruction to take effect across all departments and collection agencies. In the meantime, you can forward calls and correspondence to your representative, who will handle them on your behalf.
It is important to note that not all creditors will immediately stop calling. Some may continue to contact you directly until a settlement is reached or until they receive and process the authorization. If you are feeling harassed, you have rights under the Fair Debt Collection Practices Act, and your program representative can advise you on how to document and report inappropriate contact. The goal is to shift the negotiation burden away from you so you can focus on making your monthly deposits.
You should also expect your credit score to experience some turbulence during the early months. As accounts become delinquent or are charged off, your score may drop. This is a difficult reality of debt settlement, and it is why programs are best suited for people who are already struggling and for whom bankruptcy is a real consideration. The trade-off is the potential to resolve debts for significantly less than the full balance, which can put you in a stronger position to rebuild your credit once the program is complete. Always consult with a qualified financial advisor to understand how these dynamics apply to your specific situation.
Building Your Settlement Fund: Deposits, Timelines, and Expectations
The first few months of a debt settlement program are primarily about accumulation. You make your monthly deposit into the dedicated account, and the balance grows. The timeline for reaching a settlement varies based on your total enrolled debt, your monthly deposit amount, and the willingness of your creditors to negotiate. Some creditors settle quickly once they see a sufficient balance; others hold out longer. A typical program may take 24 to 48 months to complete, though individual settlements can occur sooner.
It is helpful to think of this phase as a marathon rather than a sprint. The discipline of making consistent deposits is the single most important factor in your program's success. Missing deposits can delay settlements, extend your timeline, and reduce your leverage. If you anticipate a temporary financial setback, communicate with your account representative as early as possible to discuss options. Many programs offer flexibility, but only if you are proactive.
You should also prepare for the possibility that one or more creditors may refuse to settle or may file a lawsuit. While this is not the norm, it can happen. Your program should have a plan for responding to legal action, often by involving a network attorney. Understanding this risk upfront helps you avoid panic if it occurs. The vast majority of enrolled debts are resolved through negotiation, but knowing the contingency plan gives you peace of mind.
Emotional and Practical Adjustments in the First 90 Days
The psychological adjustment to a debt settlement program can be as significant as the financial one. You may feel relief at having a plan, followed by anxiety when collection calls continue or when you see your credit score dip. These feelings are normal. The first 90 days are often the most challenging because you are paying into an account without yet seeing a settlement. Trusting the process requires patience and a clear understanding of why you enrolled.
Practically, you will need to adjust your budget to accommodate your monthly deposit. This may mean trimming discretionary spending, renegotiating other bills, or finding ways to increase income. Creating a simple budget that prioritizes your settlement deposit can help you stay on track. You should also set aside a small emergency fund, even if it is modest, to avoid relying on credit cards for unexpected expenses. The last thing you want is to accumulate new debt while trying to resolve old debt.
Finally, stay engaged with your program. Attend any educational webinars, read the materials provided, and ask questions whenever something is unclear. The more informed you are, the more confident you will feel. Debt settlement is not a passive process; it is a partnership between you and your negotiation team. Your active participation improves your odds of a successful outcome.
If you are ready to explore whether debt settlement is right for you, start by estimating your potential savings with a free, no-obligation assessment. The first step is simply gathering information and having an honest conversation about your goals. With the right expectations and a committed approach, the start of your debt settlement program can be the beginning of a more stable and stress-free financial future.