
Negotiating Medical Bills After Insurance Denial
Facing a denied medical claim? Learn how negotiating medical bills after insurance denial can reduce your balance. Call 8336708023 for guidance.
By Elowen Hart
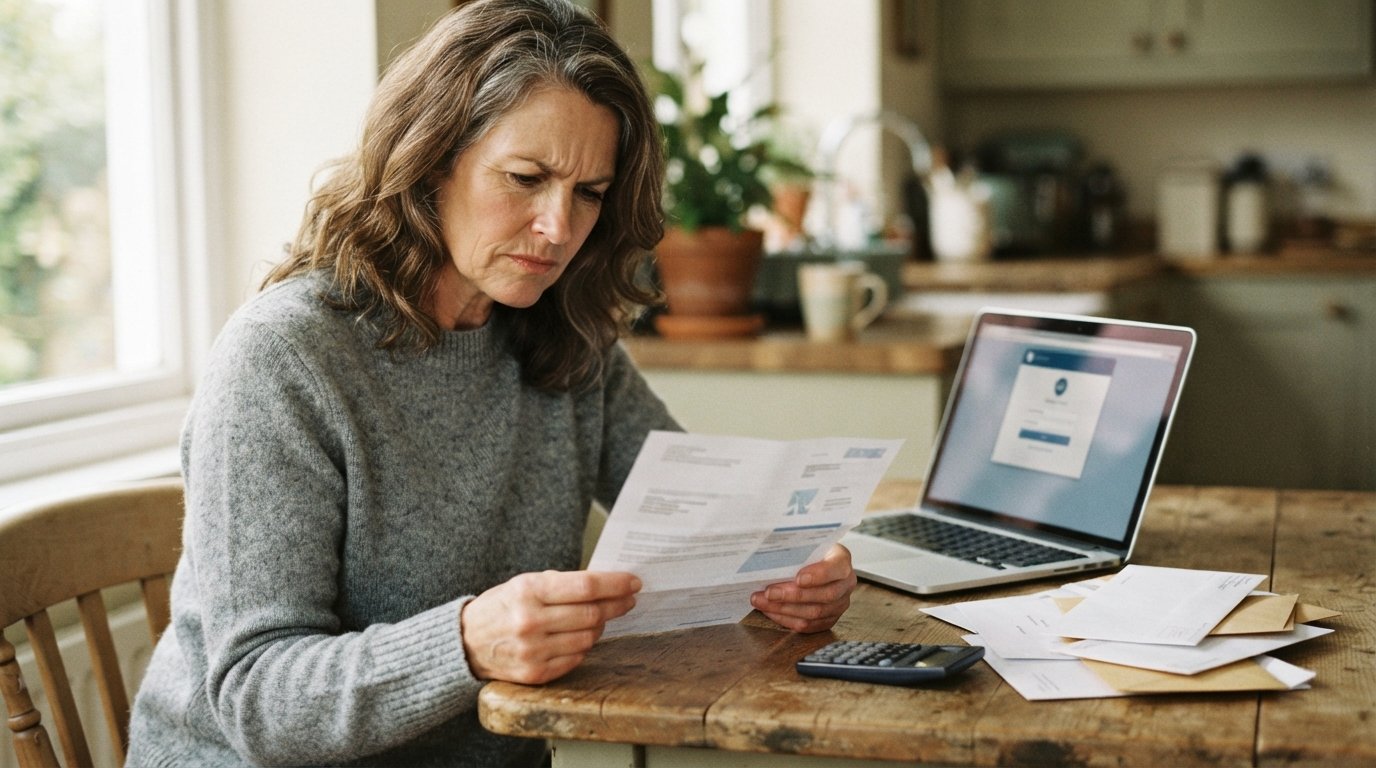
That denial letter from your health insurer can feel like a punch to the gut, especially when it arrives weeks after a procedure you assumed was covered. One moment you are recovering, and the next you are staring at a bill for thousands of dollars that your insurance company refuses to pay. The anxiety is real, and it is compounded by confusing appeals language, tight deadlines, and the fear that this debt will follow you for years. But here is the truth that hospitals and insurers rarely advertise: most medical bills are negotiable, and a denial is often just the opening bid in a longer conversation. You have more leverage than you think, and with a structured approach, you can reduce what you owe, correct billing errors, and protect your financial future.
Why Insurance Denials Happen and What They Really Mean
Before you can negotiate effectively, you need to understand why the claim was denied in the first place. Denials are not always final judgments. They are often administrative decisions based on missing information, coding errors, or a disagreement about medical necessity. According to consumer advocacy groups, a significant percentage of denied claims are overturned on appeal, which means the insurer's first answer is frequently wrong or incomplete.
Common reasons for denial include:
- Prior authorization was required but not obtained before the service
- The procedure was deemed not medically necessary by the insurer's review team
- The provider was out of network, triggering different coverage rules
- Billing codes were incorrect or inconsistent with the diagnosis
- The claim was filed past the insurer's deadline
Each of these situations opens a different door for negotiation. If the denial stems from a coding error, for example, the fix may be as simple as asking your provider to resubmit the claim with corrected information. If the insurer claims the service was not medically necessary, you and your doctor can appeal with supporting documentation. The key is to identify the specific reason and respond with evidence, not emotion.
Your First Steps After a Denial: Appeal and Document Everything
Negotiating medical bills after insurance denial begins with a formal appeal. This is not just a phone call to customer service. It is a written request, often with a specific form, that asks the insurer to reconsider its decision. Most policies have an internal appeal process, and many allow a second-level external review if the internal appeal fails. The deadline for filing an appeal is usually stated in your plan documents, so act quickly.
As you prepare your appeal, gather every piece of paper related to the claim: the denial letter, the explanation of benefits, the original bill, and any notes from your doctor. Then request a letter of medical necessity from your physician. This letter should explain why the service was essential and why alternative treatments would not have been appropriate. Insurers respond to clinical language and specific diagnoses, not general complaints.
While the appeal is pending, do not ignore the bill. Contact the hospital or provider's billing department and explain that you are appealing the denial. Ask them to place a hold on the account so it does not go to collections while the appeal is under review. Most providers will agree to this, especially if you are proactive and polite. Keep a log of every conversation, including the date, the name of the representative, and what was promised.
Negotiating with the Provider When Insurance Will Not Budge
If the appeal fails or if you decide not to appeal, the next stage is negotiating directly with the hospital, clinic, or physician. This is where your leverage increases significantly. Medical providers would rather receive something than nothing, and they are well aware that sending a bill to collections often results in a fraction of the original amount. You can use that reality to your advantage.
Start by requesting an itemized bill. This is different from the summary bill you typically receive. An itemized bill lists every single charge, including supplies, medications, and room fees. Errors are surprisingly common. You might find duplicate charges, services you never received, or prices that are far higher than the regional average. Once you have the itemized bill, compare it to your insurer's explanation of benefits. Discrepancies are your ammunition.
Next, call the billing department and ask to speak with someone who has the authority to negotiate. The first person who answers the phone may not have that power. Ask for a patient financial advocate or a supervisor. Then make your case. Explain your financial situation honestly. If you can pay a lump sum today, offer a percentage of the total, such as 40 to 60 percent, and ask if they will accept that as payment in full. Many hospitals have charity care programs or financial assistance policies that can reduce or eliminate your bill if your income falls below certain thresholds. Even if you do not qualify for full charity care, you may qualify for a discount.
If you cannot pay a lump sum, ask about interest-free payment plans. Most providers offer them, and they are far better than putting the bill on a credit card with a high interest rate. Get any agreement in writing before you make a payment.
How Debt Settlement Can Resolve Medical Bills After a Denial
Sometimes, despite your best efforts, the bill remains unmanageable. This is especially true when you have multiple medical debts from different providers, or when the amount is so large that even a reduced payment plan would strain your budget for years. In these cases, a structured debt settlement program may be a viable alternative to bankruptcy. Debt settlement involves negotiating with creditors to accept less than the full balance owed, often in a lump sum or through a series of payments.
Medical bills are considered unsecured debt, which makes them good candidates for settlement. Providers and collection agencies are often willing to negotiate because they know that medical debt is frequently the result of an emergency, not irresponsibility. If your account has already been sent to collections, the collection agency may have purchased the debt for pennies on the dollar and may be eager to settle.
That said, debt settlement is not a quick fix. It can negatively impact your credit score, and any forgiven debt over $600 may be reported to the IRS as taxable income. It is essential to work with a reputable company that explains these trade-offs clearly. Debtsend is a free matching service that connects individuals struggling with unsecured debt to third-party partners who specialize in debt relief, including settlement, consolidation, and reduction programs. The service is designed for people facing genuine financial hardship who have already explored other options. You can start with a free, no-obligation assessment to see what options may be available for your situation.
If you are considering this route, it also helps to understand what happens if a provider sues you for unpaid medical bills. In our guide on what happens when sued for unpaid medical bills, we explain the legal process, your rights, and how to respond if you receive a court summons. Knowing that information can help you make a more informed decision about whether to settle, negotiate, or seek other relief.
Building a Negotiation Strategy That Works
Whether you are appealing a denial, negotiating with a hospital, or exploring debt settlement, a clear strategy will improve your outcome. Start by prioritizing your bills. Focus on the largest balances first, as they offer the most savings potential. Then determine what you can realistically afford to pay, either as a lump sum or monthly. Do not agree to a payment plan that leaves you unable to cover basic living expenses.
When you make an offer, be specific and reasonable. For example, if you owe $5,000 and can pay $2,500 today, say so. Ask for a written confirmation that the payment will satisfy the debt in full and that any remaining balance will not be sold to another collector. Keep copies of everything. If a collector violates your rights under the Fair Debt Collection Practices Act, you may have legal recourse, but you need documentation.
Finally, consider getting help. Nonprofit credit counseling agencies can help you review your options and create a budget. But be cautious: not all counseling agencies are legitimate. Avoid any organization that charges high upfront fees or promises to fix your credit overnight. If you need a loan to cover medical expenses while you negotiate, you can explore options through services like FreeQuotes.Loans, which connects borrowers with lenders who offer personal loans, including for those with less-than-perfect credit. Just be sure to compare terms carefully and avoid payday loans with extremely high interest rates.
Protecting Yourself From Future Surprises
Once you have resolved the current bill, take steps to prevent the same situation from happening again. Always verify that your providers are in network before scheduling a procedure. If you receive a denial, act immediately. Do not wait for the bill to go to collections. And remember that you have the right to appeal any denial, often more than once.
It also helps to keep a personal health insurance file with your plan documents, explanation of benefits, and any appeal letters. If you change insurance plans, review the new policy's coverage rules and prior authorization requirements. A little preparation can save you thousands of dollars and a great deal of stress.
The bottom line is that a denial is not the end of the story. By appealing, negotiating, and exploring structured relief options, you can take control of your medical debt and move toward financial stability.